Probate vs. Non-Probate Assets: What’s the Difference?
A will is an important part of an estate plan, but it does not necessarily control everything you own. Some assets become part of your probate estate and may pass according to your will, while others transfer directly to a beneficiary or co-owner outside the probate process.
Understanding the difference between probate and non-probate assets can help you create a more coordinated estate plan, reduce confusion for your family, and avoid situations where an outdated beneficiary designation conflicts with your broader wishes.
What Are Probate Assets?
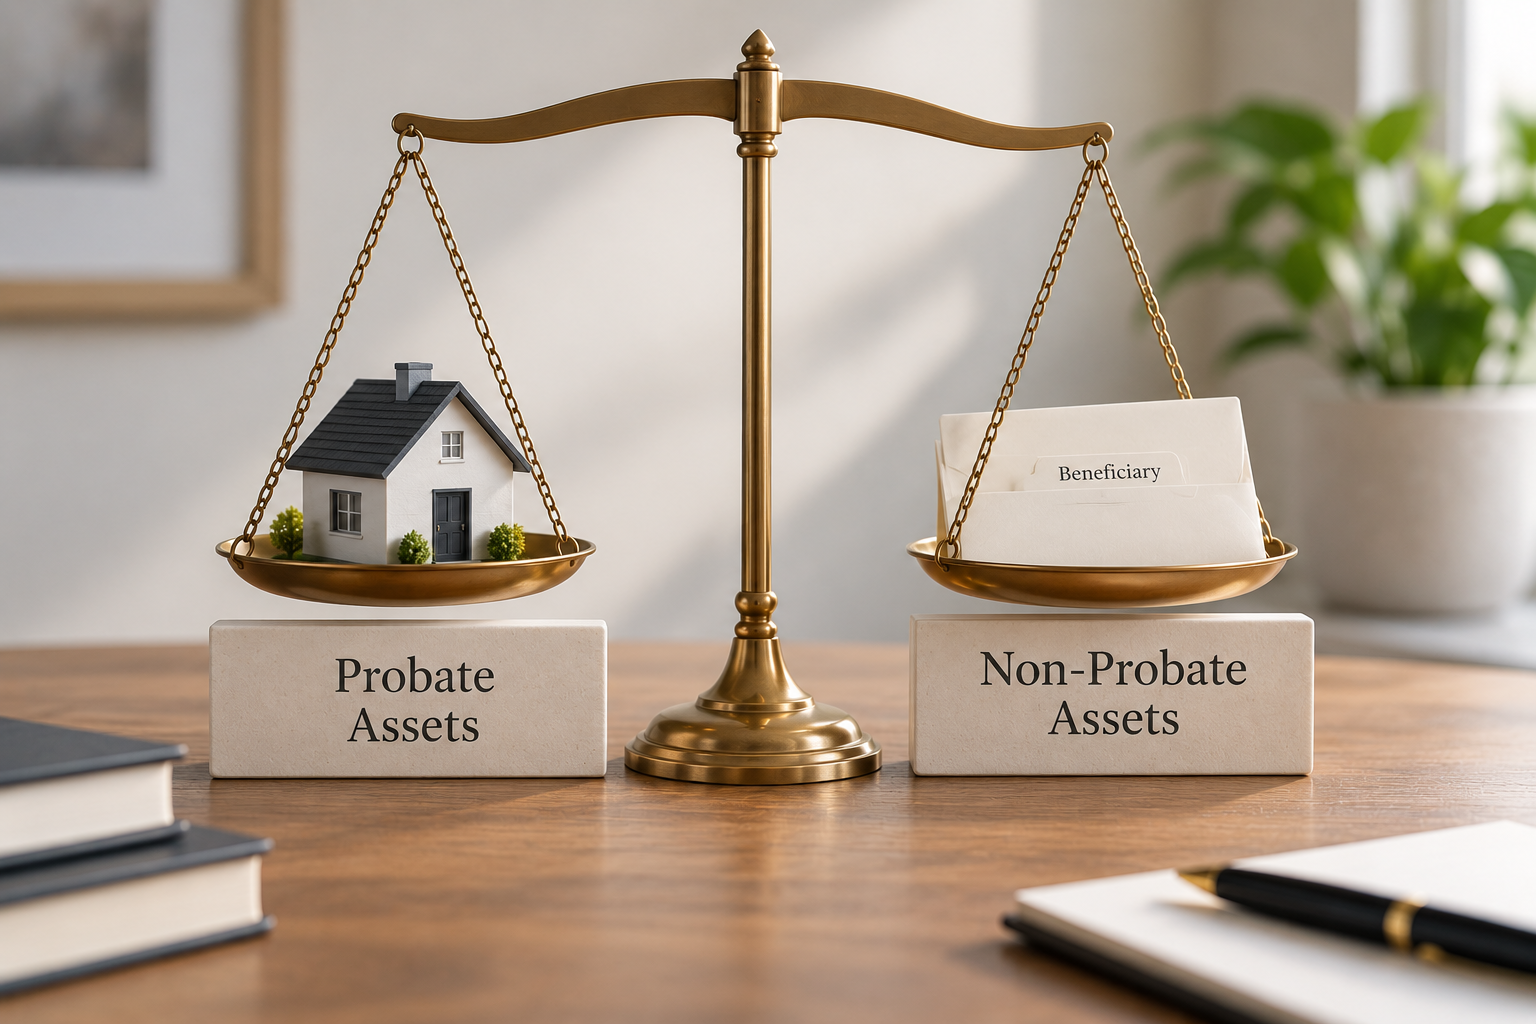
Probate assets are generally assets owned in the deceased person’s individual name that do not have another legal method of transferring at death.
When probate is required, these assets become part of the estate administered by the executor or administrator.
Common examples may include:
- Real estate owned solely by the deceased;
- Bank accounts without a payable-on-death beneficiary;
- Investment accounts without transfer-on-death instructions;
- Vehicles titled only in the deceased person’s name;
- Personal property such as jewelry, furniture, or collectibles; and
- Certain business interests.
These assets may ultimately pass according to the will. If there is no valid will, Texas intestacy laws may determine who inherits them.
What Are Non-Probate Assets?
Non-probate assets transfer through another legal arrangement rather than through the will and probate estate.
The recipient is often determined by an account designation, ownership agreement, trust, or contract established before death.
Examples can include:
- Life insurance with a named beneficiary;
- Retirement accounts with beneficiary designations;
- Payable-on-death bank accounts;
- Transfer-on-death investment accounts;
- Certain jointly owned property with survivorship rights;
- Assets held in a trust; and
- Property transferred through certain estate planning deeds.
Because these assets typically transfer outside probate, the instructions in a will generally do not override a valid beneficiary designation or survivorship arrangement.
Why Your Will Does Not Control Every Asset
One of the most common estate planning misunderstandings is assuming that a will determines who receives everything.
Consider a person whose will says that all property should be divided equally between two children. If a retirement account still names only one child as beneficiary, that account may pass entirely to the named beneficiary rather than being divided according to the will.
The same issue can occur with life insurance, POD accounts, jointly owned property, and other non-probate assets.
This is why an estate plan should coordinate the will with the way individual assets are titled and designated.
How Bank Accounts Can Transfer
A bank account can be either a probate or non-probate asset depending on how it is structured.
Individual Account Without a Beneficiary
An account owned solely by the deceased without a POD designation may become part of the probate estate.
Payable-on-Death Account
A POD account generally transfers directly to the named beneficiary after the account owner dies and the required documentation is provided.
Joint Account
A joint account may pass to a surviving owner if the account includes valid survivorship rights. Joint ownership alone does not always mean survivorship applies, so the account agreement matters.
The same type of asset can therefore receive very different treatment depending on how ownership was established.
What Happens to Real Estate?
Real estate is another area where ownership structure matters.
A home owned solely by the deceased may become a probate asset unless another transfer mechanism applies.
Property may pass differently when it is:
- Owned with valid survivorship rights;
- Properly transferred into a trust;
- Subject to a valid transfer-on-death deed or other planning arrangement; or
- Owned through an entity or other structure.
Reviewing deeds and ownership records is essential when determining whether real estate must pass through probate.
Retirement Accounts and Life Insurance
Retirement accounts and life insurance commonly pass through beneficiary designations.
These assets may include:
- 401(k) accounts;
- IRAs;
- Employer retirement plans;
- Pension benefits; and
- Life insurance policies.
When a valid beneficiary is named, the proceeds generally transfer directly to that person rather than through the will.
This makes beneficiary reviews an important part of estate planning. A designation made many years ago may no longer reflect the account owner’s current wishes.
What Happens When a Beneficiary Dies First?
Problems can arise when a named beneficiary dies before the account owner and the designation is never updated.
What happens next depends on the account terms and whether a contingent beneficiary was named.
The asset might:
- Pass to a contingent beneficiary;
- Become payable to the account owner’s estate; or
- Transfer according to the institution’s default rules.
If the asset becomes payable to the estate, it may then become subject to probate.
Naming and periodically reviewing contingent beneficiaries can help reduce this risk.
Assets Held in a Trust
Assets properly transferred into a trust are generally managed according to the trust agreement rather than the will.
After the trust creator dies, a successor trustee may take responsibility for administering the trust and distributing property according to its terms.
However, creating a trust document alone is not enough.
Assets that were supposed to be placed in the trust but were never properly retitled may still become probate assets. This is why trust funding is an important part of creating a complete trust-based estate plan.
Business Interests Can Require Additional Planning
Business ownership does not always transfer simply through a will.
Operating agreements, partnership agreements, shareholder agreements, buy-sell arrangements, or other contracts may determine what happens to an ownership interest after death.
A business owner’s estate plan should coordinate these agreements with:
- The will;
- Trusts;
- Beneficiary arrangements;
- Business succession planning; and
- Other ownership documents.
Conflicting instructions can create uncertainty for family members and business partners.
What Happens If There Is No Will?
If someone dies without a valid will, probate assets may pass according to Texas intestacy laws.
Non-probate assets generally continue to transfer according to their own beneficiary, ownership, or contractual arrangements.
For example, a life insurance policy with a valid beneficiary does not normally become subject to intestacy simply because the policyholder did not have a will.
This distinction makes asset ownership important even for someone without a formal estate plan.
Can Non-Probate Assets Still Create Estate Problems?
Yes.
Avoiding probate does not automatically mean an asset fits correctly into the estate plan.
Problems may arise when:
- A former spouse remains named as beneficiary;
- One child receives a large non-probate account while the will divides other assets equally;
- A beneficiary dies and no contingent beneficiary is named;
- An account designation conflicts with the family’s understanding of the estate plan; or
- Assets intended for a trust were never transferred into it.
These issues can create unintended distributions and family disagreements even when the legal transfer itself is straightforward.
Coordinating Probate and Non-Probate Assets
A comprehensive estate plan should consider both categories together.
That means reviewing:
- Wills;
- Trusts;
- Bank accounts;
- Investment accounts;
- Retirement plans;
- Life insurance;
- Real estate ownership;
- Business interests; and
- Beneficiary designations.
The goal is not necessarily to make every asset probate or every asset non-probate. Instead, the goal is to make sure each asset transfers in a way that supports the overall estate plan.
When Should Beneficiary Designations Be Reviewed?
Reviewing beneficiary designations can be especially important after:
- Marriage;
- Divorce;
- The birth or adoption of a child;
- The death of a beneficiary;
- A major change in assets;
- Retirement;
- Creating or updating a trust; or
- Significant changes in family relationships.
Periodic reviews can also catch outdated information before it creates a problem.
Probate Avoidance Is Not the Only Goal
Avoiding probate can be useful in many estate plans, but it should not be the only consideration.
An asset transfer strategy should also account for:
- Who should receive the property;
- When they should receive it;
- Whether protection or management is needed;
- Tax and financial considerations;
- Family circumstances; and
- How the transfer fits with the rest of the estate plan.
A direct beneficiary designation may be simple, but a trust may offer greater control for certain beneficiaries or assets.
Make Sure Your Estate Plan and Your Assets Tell the Same Story
A well-written will is only one part of determining what happens to your property after death.
If beneficiary designations, account ownership, deeds, trusts, and business agreements point in different directions, your assets may not transfer the way you expect.
At Henington Lewis Law Firm PLLC, we help Texas families coordinate wills, trusts, beneficiary designations, property ownership, and other estate planning tools so they work together. Reviewing how your assets are structured today can help prevent confusion and ensure your estate plan better reflects your wishes when the time comes.
Frequently Asked Questions
What is the difference between probate and non-probate assets?
Probate assets pass through estate administration, while non-probate assets generally transfer directly through a beneficiary designation, trust, or ownership arrangement.
Does a will control non-probate assets?
Generally, no. Valid beneficiary designations and survivorship arrangements usually determine how non-probate assets transfer.
Are bank accounts probate assets?
They can be. An individually owned account without a POD beneficiary may require probate, while a valid POD account may transfer directly.
Is life insurance a probate asset?
Usually not when a valid beneficiary is named. If the estate is the beneficiary, the proceeds may become part of the probate estate.
Are assets in a trust subject to probate?
Assets properly transferred into a trust generally avoid probate and are administered according to the trust terms.
What happens to probate assets if there is no will?
They generally pass according to Texas intestacy laws when there is no valid will.
Our Austin, TX Office Location
Related Posts
Probate vs. Non-Probate Assets: What’s the Difference?
A will is an important part of an estate plan, but it does not necessarily control everything you own. Some assets become part of your probate estate and may pass according to your will, while others transfer directly to a beneficiary or co-owner outside the…
Can You Disinherit a Child or Family Member in Texas?
Disinheriting a child or another family member is a serious estate planning decision. In Texas, you generally have broad freedom to decide who should receive your property after death, but the way you express that decision matters. A poorly drafted will or unclear estate plan…
What Happens to Bank Accounts After Someone Dies?
When someone dies, their bank accounts do not all follow the same process. What happens next depends on how the account is titled, whether a beneficiary is named, whether another person is a joint owner, and whether the account becomes part of the probate estate.For…
Planning for Incapacity: Who Will Manage Your Finances and Healthcare?
Estate planning is not only about what happens after death. It should also address what happens if an illness, injury, or cognitive decline leaves you unable to manage your finances or make healthcare decisions on your own.Without a plan, family members may be unsure who…
Protecting an Inheritance From Divorce and Creditors
Receiving an inheritance can provide long-term financial security, but inherited assets are not automatically protected from every future risk. Divorce, creditor claims, lawsuits, poor financial decisions, and commingling inherited property with marital assets can all create complications that affect how much of an inheritance ultimately…
After a Death in the Family: Essential Estate Steps in Texas
Losing a family member brings emotional and practical challenges at the same time. Along with funeral arrangements and supporting loved ones, families may suddenly face questions about property, bank accounts, bills, estate documents, and what comes next. In Texas, no single process applies to every estate.…
Whether you need a personalized estate plan or help handling a civil dispute, we're here to help
Take the first step toward protecting your legacy and giving your family lasting peace of mind. Whether you need a personalized estate plan or help handling a civil dispute, we're here to help.


Quick Links
Disclaimer: This website is for informational purposes only and constitutes an attorney advertisement. The content on this site is not intended to provide legal advice or create an attorney-client relationship. Viewing or interacting with this website does not establish such a relationship between you and our firm. Do not send confidential or sensitive information through this website or its contact forms. Communications through the website are not secure and may not be protected under attorney-client privilege. If you require legal advice or representation, please contact our office directly to arrange a consultation. The information provided on this site is general in nature and may not apply to your specific situation. You should consult an attorney for advice tailored to your circumstances. Past outcomes or case results referenced on this site do not guarantee future results. Every legal matter is unique, and results depend on the specific facts and applicable law. Jurisdictional Limitation: Our firm is licensed to practice law in Texas. This website is not intended to solicit clients outside of this jurisdictions. Copyright Notice: All content on this site is copyrighted and may not be reproduced without permission.
© 2026 Henington Lewis Law Firm PLLC. All Rights Reserved.