Planning for Couples With Unequal Assets or Incomes

If one spouse stopped earning tomorrow, would the other person’s accounts, property, and estate planning documents provide the financial protection they assume is already there?

For couples with significantly different incomes or assets, that question can reveal gaps that are easy to overlook while both spouses are alive and managing the household together. Retirement savings may be concentrated in one name, a home or business may belong primarily to one spouse, and inherited property may have its own considerations. Estate planning provides a way to look at those differences together and determine what would actually happen if either spouse could no longer manage the financial role they have today.
(512) 737-8404

Planning for Couples With Unequal Assets or Incomes

Understanding Financial Imbalances in an Estate Plan

Unequal finances are not limited to differences in salary. They can develop gradually through career decisions, property ownership, inheritances, business interests, investment growth, or time spent outside the workforce.

For estate planning purposes, what matters is not simply which spouse has the higher net worth. It is understanding where the household’s financial security actually sits and what would happen to those resources after death or incapacity.

A couple’s financial picture may include:

  • Retirement savings concentrated in one spouse’s name
  • Real estate owned individually or together
  • Business interests
  • Investment and brokerage accounts
  • Inherited assets
  • Life insurance
  • Joint and individual financial accounts
  • Property acquired before the marriage

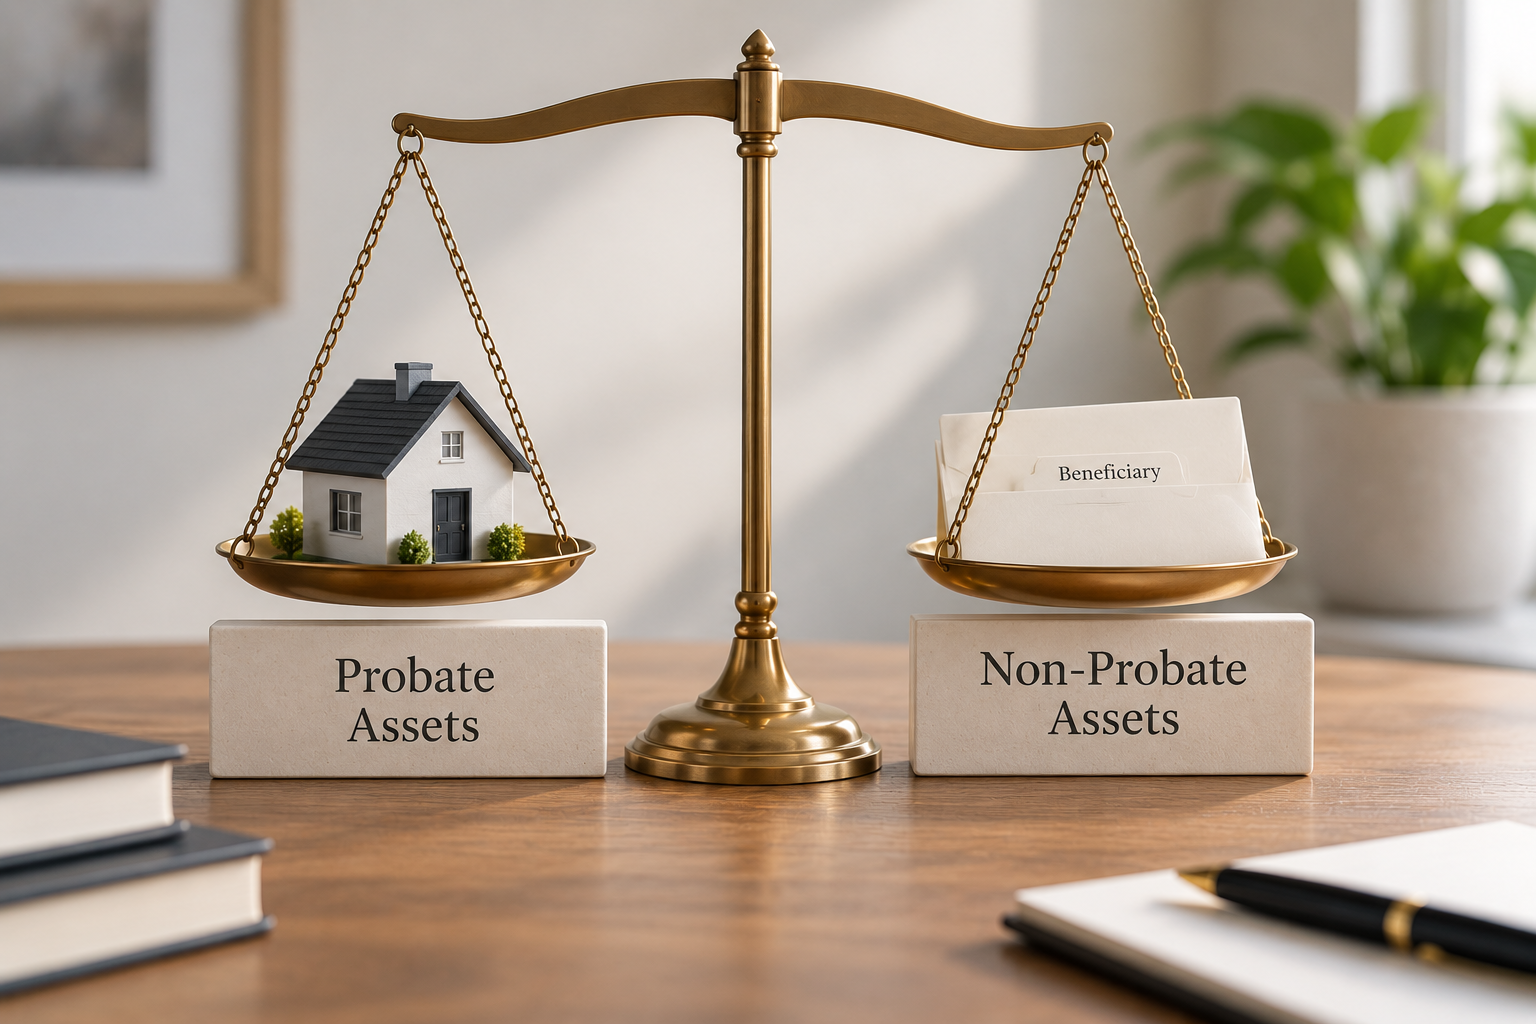
Some of those assets may pass through a will or trust, while others may transfer through beneficiary designations, ownership arrangements, or other mechanisms. Understanding the difference between probate and non-probate assets provides a clearer starting point for evaluating how the overall plan would work.

Unequal Income Can Create Different Financial Needs

Income differences can affect more than how much each spouse saves.

A higher-earning spouse may fund a larger portion of the mortgage, household expenses, retirement savings, insurance, or education costs. If that income disappears, the surviving spouse may need to continue many of those same financial responsibilities with very different resources.

That can make it useful to consider expenses such as:

  • Mortgage and housing costs
  • Health and other insurance
  • Everyday household expenses
  • Education costs
  • Outstanding debts
  • Long-term savings needs
  • Costs associated with maintaining property

The goal is not necessarily to equalize what each spouse owns. It is to understand whether the surviving spouse would have access to the resources needed to manage the financial life the couple built together.

Property Ownership Can Affect the Plan

When one spouse owns significantly more property, understanding how that property is characterized becomes important.

Texas distinguishes between separate and community property. Property acquired during marriage is generally presumed to be community property, while property owned before marriage or received by gift or inheritance may qualify as separate property.

This distinction can become particularly relevant when one spouse:

  • Entered the marriage owning a home or other real estate
  • Received a substantial inheritance
  • Built a business before the marriage
  • Has significant investments accumulated earlier in life
  • Owns property separately from the other spouse

Property ownership and marital property rules can affect what each spouse can transfer and what happens when one dies. For that reason, estate planning should begin with a clear understanding of how major assets are owned rather than assuming that marriage alone determines the outcome.

A Will May Control Only Part of the Wealth

A will can provide important instructions, but it does not necessarily control every asset a couple owns.

Retirement accounts, life insurance policies, payable-on-death accounts, and certain other financial assets may transfer according to beneficiary designations or account arrangements.

That distinction becomes especially important when a large portion of the household’s wealth is concentrated in accounts belonging to one spouse.

For example, a couple may have wills that divide property one way while a retirement account names a beneficiary who causes a substantial portion of the wealth to transfer differently. The documents may each be valid while still producing an overall result the couple did not expect.

This is why beneficiary designations should be reviewed alongside wills and trusts. The same consideration applies to 401(k)s and other retirement accounts.

A Trust Can Address More Than Who Inherits

When spouses have significantly different assets, the planning question may not simply be who receives property after death. Couples may also want to decide how assets should be managed and used over time.

Depending on the circumstances, a trust can provide greater control over those decisions.

A trust may be designed to:

  • Provide financial support for a surviving spouse
  • Establish how certain assets can be used
  • Manage property for children or other beneficiaries
  • Set instructions for future distributions
  • Provide continuity in managing particular assets
  • Determine what happens to remaining property later

Not every couple with unequal wealth needs a trust. The value of a trust depends on the assets involved, the beneficiaries, and what the couple wants to accomplish.

For couples considering this approach, understanding what assets should be placed in a trust can help clarify how the trust would fit into the broader plan.

Inherited Wealth May Come With Different Goals

A financial imbalance can also develop suddenly.

One spouse may inherit money, real estate, investments, or an interest in a family business. While that inheritance may become an important part of the couple’s financial life, the spouse who received it may also have specific ideas about where the property should eventually go.

For example, someone may want an inheritance to help support a spouse during their lifetime while ultimately preserving certain assets for children or other relatives.

Those goals should be addressed deliberately rather than assumed.

Inherited property can raise questions about ownership, management, beneficiary choices, and how the inheritance should coordinate with the rest of the estate. Addressing those issues while both spouses can participate in the planning process can make the intended outcome clearer.

Business Ownership Requires a Different Conversation

For some couples, the largest financial imbalance is not sitting in a bank account. It is tied up in a business.

A business can represent a substantial portion of one spouse’s wealth while providing much of the household’s income at the same time. If that spouse dies or becomes incapacitated, the family could face questions involving both ownership and ongoing financial support.

Planning may need to consider:

  • Who should receive the ownership interest
  • Whether the surviving spouse should be involved in the business
  • Who is capable of managing operations
  • Whether there are other owners or partners
  • How the surviving spouse would receive financial support
  • Whether the business should eventually pass to children or other beneficiaries

Simply transferring a business interest does not necessarily replace the income or management role the owner previously provided. The business therefore needs to be considered as part of the household’s broader estate plan.

Incapacity Can Expose Financial Gaps Too

Death is not the only event that can reveal an imbalance between spouses.

In some households, one spouse handles most investments, manages the business, communicates with financial professionals, or oversees major accounts. If that person becomes unable to manage those responsibilities, the other spouse may suddenly need access to financial information and authority they have never previously needed.

Planning for incapacity may involve reviewing:

  • Financial powers of attorney
  • Medical decision-making documents
  • Trust provisions
  • Access to important financial information
  • Authority to manage property or business interests
  • The people chosen to step in when necessary

These arrangements can be particularly important when financial responsibilities are concentrated with one spouse rather than shared equally.

Equal Is Not Always the Same as Fair

A balanced estate plan does not necessarily require every asset to be divided in half.

Different assets may need to accomplish different goals. The surviving spouse may need continued access to the home and enough resources to cover living expenses. A business may need to pass to someone capable of operating it. Other assets may be intended for children or family members.

Looking at each asset separately can make the plan seem uneven even when the overall arrangement reflects what the couple wants.

A more useful approach is to consider how the pieces work together:

  • What does the surviving spouse need?
  • Which assets can provide income or liquidity?
  • Are there assets intended for other beneficiaries?
  • Does either spouse want certain property to remain within their family?
  • How will beneficiary-designated accounts affect the overall distribution?
  • Who should manage assets that cannot simply be divided?

The answers may lead to different distributions for different assets while still creating a coordinated plan.

Both Spouses Should Know How the Plan Works

When one spouse earns substantially more or controls most of the household’s assets, important financial decisions can gradually become concentrated with that person.

Estate planning is an opportunity to make those arrangements visible to both spouses.

Each spouse should understand:

  • Which assets are owned individually and jointly
  • Where major financial accounts are held
  • Who is named as beneficiary
  • Which assets would pass through probate
  • What the surviving spouse would receive
  • How ongoing household expenses could be supported
  • Who could manage finances during incapacity
  • Whether certain assets are intended for other beneficiaries

A coordinated estate and legacy plan can bring those decisions together rather than relying on assumptions about what will happen.

Plan for the Financial Life You Actually Have

Unequal assets or incomes do not necessarily require a more complicated estate plan. They do require a clear understanding of where the household’s wealth is held, how it would transfer, and what each spouse would need if the other were no longer able to contribute financially.

Reviewing wills, trusts, beneficiary designations, property ownership, business interests, and incapacity documents together can reveal gaps that may not be obvious when each piece is considered separately.

Henington Lewis Law Firm PLLC helps couples in Austin and Central Texas create estate plans that reflect their property, financial responsibilities, and long-term goals. If you and your spouse have significantly different assets or incomes, contact our firm to discuss how your estate plan can address those differences.

Frequently Asked Questions

How should couples with different incomes approach estate planning?

Couples should look beyond how much each person earns and consider where their assets are held, how property is owned, which accounts have beneficiary designations, and what each spouse would need if the other died or became incapacitated. The goal is to coordinate those pieces within the overall estate plan.

Does the higher-earning spouse need a different estate plan?

Not necessarily a separate plan, but differences in income and asset ownership may require additional consideration. If most retirement savings, business interests, or other significant assets are concentrated with one spouse, the couple should consider how the other spouse would be financially protected.

Does my spouse automatically have access to assets in my name if I die?

Not always. What happens to an asset can depend on the type of property, how it is owned, whether there is a beneficiary designation, and the estate planning documents in place. Marriage alone does not mean every individually held asset will transfer in the same way.

Should both spouses be beneficiaries of each other’s retirement accounts?

The appropriate beneficiary designation depends on the type of retirement plan, applicable rules, and the couple’s goals. Retirement accounts should be reviewed as part of the broader estate plan rather than assuming the will determines who receives them.

Can a trust protect a lower-earning spouse?

Depending on how it is structured, a trust can provide financial support for a surviving spouse while establishing instructions for how assets are managed and eventually distributed. Whether a trust is appropriate depends on the couple’s assets, beneficiaries, and long-term goals.

How should inherited property be handled when one spouse has significantly more assets?

Inherited property may require separate consideration because the spouse who received it may have specific goals for its use and eventual distribution. The estate plan can address how that property should benefit a surviving spouse while also considering children or other intended beneficiaries.
Our Austin, TX Office Location

What Happens If Your Executor Dies Before You?

Naming an executor is an important part of creating a will, but that choice may have been made years or even decades before the executor is ever needed. If the person you selected dies before you, your will does not automatically become invalid.

What happens next depends largely on whether your will names an alternate executor and whether you update the document during your lifetime. Understanding those possibilities can help prevent uncertainty about who will eventually be responsible for administering your estate.

(512) 737-8404

What Happens If Your Executor Dies Before You

Your Will Does Not Become Invalid

The death of a named executor generally does not invalidate the rest of a valid will.

Your instructions about who should inherit your property can remain effective even if the person originally selected to administer the estate is no longer available. The issue is instead who will carry out the responsibilities assigned to the executor.

That distinction matters because an executor can be responsible for tasks such as:

  • Identifying and securing estate property
  • Managing estate assets during probate
  • Addressing valid debts and claims
  • Handling required court filings
  • Distributing property according to the will
  • Completing other responsibilities required during the probate process in Texas

The estate therefore still needs someone legally authorized to perform those duties.

An Alternate Executor Can Simplify the Situation

A well-prepared will often names more than one potential executor.

For example, you might name one person as your first choice and another person to serve if the first executor dies, declines to serve, or is otherwise unable to act.

If your primary executor dies before you but a qualified alternate is already named, that person may be able to seek appointment when the will is eventually admitted to probate.

Naming a successor in advance can provide a clear next choice without requiring your family to determine whom you would have preferred after your death.

What If Your Will Does Not Name a Backup Executor?

Not every will includes an alternate.

If the person named as executor cannot serve and the will does not provide another eligible choice, the probate court may need to appoint someone to administer the estate.

Texas law establishes an order of priority for people who may be entitled to serve as administrator when there is no executor able and willing to act. The circumstances of the estate and the qualifications of the proposed administrator can affect the appointment.

This means the person ultimately responsible for the estate may not be someone you personally selected.

The Court Still Considers Whether Someone Is Qualified to Serve

Being named in a will does not guarantee that someone will ultimately serve as executor. Texas law identifies circumstances that can disqualify a person from serving as executor or administrator, making it important to choose both primary and alternate executors carefully.

Texas law identifies circumstances that can make a person unsuitable or legally disqualified from serving as executor or administrator. For that reason, an alternate executor should be chosen with the same care as the primary executor.

When reviewing your choices, consider whether the person:

  • Is willing to take on the responsibility
  • Can manage financial and administrative tasks
  • Is likely to remain available
  • Can work appropriately with beneficiaries
  • Understands the importance of following the will and probate requirements

The goal is not simply to have another name in the document. It is to select someone who could realistically handle the role.

You Can Change Your Executor While You Are Alive

If you learn that your executor has died, you do not have to leave the issue for the probate court to resolve later.

While you are alive and have the required legal capacity, you can review your will and determine whether the executor provisions should be updated. Depending on the circumstances, that may involve properly amending the existing will or executing a new will.

This can also be an opportunity to review whether other parts of the document still reflect your wishes.

A will created many years ago may contain outdated choices involving:

  • Beneficiaries
  • Alternate beneficiaries
  • Executors and successor executors
  • Guardians
  • Property that you no longer own
  • Family circumstances that have changed

If one important provision is outdated, reviewing the rest of the document can help identify other decisions that may also need attention.

Your Backup Executor May Need an Update Too

Sometimes the primary executor is still available, but the person named as the alternate has died or is no longer an appropriate choice.

That situation is easy to overlook because the backup may never be needed. However, successor appointments exist precisely for unexpected circumstances.

Consider whether your will currently provides enough depth if:

  • Your first choice cannot serve
  • Your second choice cannot serve
  • One of the named individuals has died
  • Relationships with named executors have changed
  • An executor has moved or developed circumstances that could make serving difficult

Reviewing both the primary and successor appointments can make the plan more resilient.

What If the Executor Dies After You but Before Probate Is Finished?

A different issue arises when an executor survives you, begins administering the estate, and then dies before probate is complete.

The estate still needs someone with legal authority to finish the administration. The next step can depend on the terms of the will, whether another executor was named, and the stage of the probate proceeding.

Texas law provides for the appointment of a successor representative when further administration is necessary after a personal representative dies, resigns, or is removed.

This situation can involve additional court procedures, but the executor’s death does not simply leave the estate permanently unfinished.

Choosing an Executor Close to Your Age Deserves Consideration

There is no requirement that an executor be younger than you. A spouse, sibling, close friend, or other contemporary may be the person you trust most.

Still, longevity and availability are practical considerations when creating a plan that may not be needed for many years.

If your primary executor is close to your age or older, naming one or more capable successors can provide additional protection. The same principle can apply when selecting trustees and other people who may have responsibilities under your estate and legacy plan.

The strongest choice today may not necessarily be available decades from now.

An Executor Review Should Be Part of Maintaining Your Will

Estate planning documents should continue to reflect the people and circumstances in your life.

An executor who dies before you is an obvious reason to revisit a will, but death is not the only reason an appointment can become outdated. Someone may no longer want the responsibility, your relationship may change, or another person may become better suited to the role.

Reviewing your executor choices periodically allows you to decide who should handle your estate rather than leaving that decision unresolved until probate.

Keep Your Executor Choices Current

Your will can remain valid even when a named executor dies before you, but an outdated appointment can create an issue that is often easier to address during your lifetime.

Naming qualified successor executors and reviewing those choices as circumstances change can provide clearer instructions for the people who will eventually administer your estate.

Henington Lewis Law Firm PLLC helps individuals and families in Austin and Central Texas prepare and review wills as part of a coordinated estate plan. If the executor or successor named in your current will has died or is no longer the person you want to serve, contact our firm to discuss updating your plan.

Frequently Asked Questions

What happens if the executor named in my will dies before me?

Your will does not automatically become invalid. If you named an alternate executor, that person may be able to seek appointment when your estate enters probate. If no alternate is available, the probate court may need to appoint someone to administer the estate.

Do I need to change my will if my executor dies?

Not necessarily for the will to remain valid, but it is a good reason to review the document. Updating your executor provisions allows you to choose who should serve rather than leaving the appointment unresolved until probate.

Can I name more than one backup executor in my will?

A will can provide for successor executors who may serve if earlier choices cannot or will not act. Naming additional qualified successors can help provide continuity if your first choice is unavailable when the will is eventually needed.

What happens if both my executor and alternate executor die before me?

If none of the executors named in your will can serve, the court may need to appoint a qualified person to administer the estate. This is one reason executor appointments should be reviewed periodically.

Can an executor refuse to serve after I die?

Yes. Being named as executor does not require someone to accept the appointment. If the person declines to serve, an alternate named in the will may be considered. If no named executor is available, the court may need to appoint another qualified person.

What happens if an executor dies while administering an estate?

If an executor dies before the estate administration is complete, another personal representative may need to be appointed to handle the remaining responsibilities. The next steps can depend on the will, the status of the probate proceeding, and whether further administration is necessary.


Our Austin, TX Office Location

Second Marriages: Protecting Your Spouse and Your Family

A second marriage can bring together two financial lives that were built long before the relationship began. Each spouse may enter the marriage with a home, retirement savings, investments, business interests, or property intended for children from a previous relationship.

That can make estate planning more complicated than simply leaving everything to a spouse. Many couples want to provide financial security for each other while also making sure certain assets eventually reach their own children or other family members. Without coordinated planning, those two goals may not always lead to the same result.

(512) 737-8404

Second Marriages: Protecting Your Spouse and Your Family

Start With What Each Spouse Already Owns

One of the first considerations in a second marriage is understanding what each person brings into the relationship.

Texas distinguishes between separate and community property. In general, property owned before marriage and property received during marriage by gift or inheritance can qualify as separate property, while property acquired during the marriage is generally community property. Understanding these Texas marital property rules can be particularly important when each spouse enters the marriage with assets accumulated earlier in life. 

For couples entering a second marriage, the financial picture may include:

  • A home purchased before the marriage
  • Retirement and investment accounts accumulated over many years
  • Property received through a previous inheritance
  • Business interests
  • Life insurance policies
  • Savings and other financial accounts
  • Property acquired together after the marriage

Understanding which assets belong to which spouse, and how they are titled, creates a clearer starting point for deciding what should happen to them later.

Leaving Everything to Your Spouse May Not Accomplish Both Goals

For some couples, leaving assets outright to the surviving spouse is exactly what they want. In other families, it can create a problem.

Consider a spouse who has children from a previous marriage and leaves most assets outright to the new spouse. Once those assets belong to the surviving spouse, the original owner’s estate plan generally no longer controls how the surviving spouse ultimately distributes property that became theirs.

The surviving spouse’s own will or trust may benefit different children or family members. The survivor could also remarry, change estate planning documents, sell property, or use assets during their lifetime.

This does not mean the surviving spouse should be excluded. Instead, the estate plan may need to distinguish between providing for a spouse and determining who ultimately inherits particular assets.

For families combining households and children from previous relationships, these considerations can overlap with broader estate planning for blended families.

A Trust Can Balance Competing Priorities

A trust can provide options when someone wants a surviving spouse to benefit from property without necessarily giving the surviving spouse complete control over where the remaining assets eventually go.

Depending on how the trust is structured, it may provide for a spouse during their lifetime while establishing instructions for the remaining property after that spouse dies.

For example, a plan might be designed to:

  • Provide income or financial support to the surviving spouse
  • Allow the spouse to use certain assets during their lifetime
  • Establish rules for distributions from the trust
  • Preserve remaining assets for children or other beneficiaries
  • Appoint a trustee to manage the property according to the trust terms

The appropriate arrangement depends heavily on the couple’s assets and goals. A trust should not be treated as a one-size-fits-all solution simply because someone is entering a second marriage.

Understanding the different roles of a will and trust can help couples decide which tools fit those goals.

The Family Home Deserves Special Attention

A home can be one of the most sensitive assets in a second marriage.

One spouse may have purchased the property years before the marriage and want a new spouse to continue living there if they die first. At the same time, that spouse may ultimately want the property to pass to children from a previous relationship.

Simply stating who should receive the house does not resolve every issue. Texas law provides specific homestead protections that can affect the rights of a surviving spouse and how the property is handled after death. 

A plan involving a home should therefore consider practical questions such as:

  • Can the surviving spouse continue living in the property?
  • Who will ultimately inherit the home?
  • Who will be responsible for taxes, insurance, maintenance, and repairs?
  • What happens if the surviving spouse wants to move?
  • How does the property’s ownership fit with the rest of the estate plan?

Addressing these issues in advance can provide much more clarity than leaving the family to resolve them after a death.

Beneficiary Designations Can Change the Outcome

A carefully drafted will does not necessarily control every asset.

Retirement accounts, life insurance policies, and certain financial accounts may transfer according to beneficiary designations or other contractual arrangements. That means someone who remarries should review more than the will itself.

An older beneficiary designation could still name a former spouse, children, or another person. A newly updated designation could also unintentionally change the balance between what a spouse receives and what children receive.

Assets worth reviewing include:

  • 401(k)s and other employer retirement plans
  • IRAs
  • Life insurance
  • Payable-on-death accounts
  • Transfer-on-death arrangements
  • Other accounts with named beneficiaries

Because retirement accounts may pass outside probate, beneficiary designations should be reviewed as part of the overall estate plan rather than as a separate administrative task.

Property Agreements and Estate Plans Should Work Together

Some couples enter a second marriage with a premarital agreement, while others make agreements about property after marriage.

Those agreements and the estate plan should not be treated as unrelated documents. Texas law allows spouses to make certain agreements concerning separate and community property, including agreements that can change the character of property.

If an estate plan says one thing while a marital property agreement, property title, or beneficiary designation points in another direction, the result may be different from what the couple expected.

A review should therefore consider the entire arrangement, not just the will sitting in a file.

Choosing the Right Trustee or Executor Matters

Second marriages can also make fiduciary choices more sensitive.

Naming a surviving spouse as executor or trustee may make sense in some families. In others, asking a spouse to manage assets that will eventually pass to stepchildren can create tension or competing expectations.

The same concern can arise when an adult child is asked to manage assets intended to support a stepparent.

When selecting an executor or trustee, consider:

  • The person’s ability to manage financial responsibilities
  • Their relationship with the beneficiaries
  • Whether family dynamics could make the role difficult
  • Whether a neutral or independent trustee may be appropriate
  • Who should serve if the first choice cannot act

The goal is not simply to name someone trustworthy. The person should also be suited to the responsibilities and family circumstances involved.

Both Spouses Need to Understand the Plan

Estate planning for a second marriage works best when the objectives are clear.

One spouse may assume the survivor will be financially secure, while the other assumes certain property will immediately pass to children. Those expectations can conflict if the documents and account arrangements have not been coordinated.

Couples should understand:

  • What the surviving spouse receives
  • Which assets pass directly to children or other beneficiaries
  • Which assets may remain in trust
  • Who controls trust property
  • What happens to the family home
  • How beneficiary-designated accounts are distributed
  • Who ultimately receives remaining assets after both spouses die

These conversations may involve difficult decisions, but making those decisions during the planning process can reduce uncertainty later.

Build a Plan Around Both Sides of the Family

A second marriage does not require choosing between protecting a spouse and protecting an inheritance for children. The more important question is how each goal should be addressed and which assets should support it.

Wills, trusts, beneficiary designations, property ownership, and marital agreements can all affect the outcome. When those pieces are reviewed together, couples can create a plan that reflects both the new marriage and the financial commitments that existed before it.

Henington Lewis Law Firm PLLC helps individuals and couples in Austin and Central Texas develop estate and legacy plans for changing family and financial circumstances. If you are entering a second marriage or already have an estate plan that predates your marriage, contact our firm to discuss whether your current documents still reflect your goals.

Frequently Asked Questions

Should I update my estate plan after a second marriage?

Yes. A second marriage can change your family structure, property ownership, beneficiaries, and financial priorities. Reviewing your will, trust, beneficiary designations, and other estate planning documents can help ensure your plan reflects both your marriage and your existing family obligations.

How can I provide for my spouse while protecting an inheritance for my children?

Depending on your circumstances, a trust may allow you to provide financial support or access to certain assets for a surviving spouse while directing remaining property to children or other beneficiaries later. The appropriate structure depends on your assets, family relationships, and long-term goals.

Does my spouse automatically inherit everything if I die in Texas?

Not necessarily. What a surviving spouse inherits can depend on whether there is a valid will or trust, whether property is separate or community property, how particular assets are titled, beneficiary designations, and which family members survive the deceased spouse.

What happens to a house owned before a second marriage?

A home owned before marriage may be separate property, but ownership is not the only consideration. Texas homestead protections and the rights of a surviving spouse may affect what happens to the property after death, so the home should be specifically addressed as part of the estate plan.

Should I change my beneficiaries when I remarry?

Beneficiary designations should be reviewed after remarriage. Retirement accounts, life insurance policies, and certain financial accounts may transfer according to their beneficiary designations rather than a will, making it important to coordinate those designations with the rest of your estate plan.

Can my spouse and I have different estate planning goals?

Yes. Spouses in a second marriage may enter the relationship with different assets, children, beneficiaries, and financial obligations. An estate plan can account for those differences while establishing how each spouse wants property managed and distributed.


Our Austin, TX Office Location

Your 40s Are a Critical Time to Review Your Will and Trust

By your 40s, your financial and family life may look very different from when you first created an estate plan. A will or trust prepared years ago may still reflect an earlier stage of your life, even as your family, property, savings, and responsibilities have continued to change.

Reviewing your estate plan during this decade is not simply about updating old documents. It is an opportunity to make sure the people you have chosen, the assets you now own, and the instructions you have left behind still work together.

(512) 737-8404

Your 40s Are a Critical Time to Review Your Will and Trust

Your Estate May Be More Complex Than It Was Ten Years Ago

Many people accumulate significant assets gradually. There may never be a single moment when an estate suddenly feels complicated.

Over time, however, your financial picture may grow to include:

  • A primary residence
  • Additional real estate
  • Retirement accounts
  • Investment or brokerage accounts
  • Life insurance
  • Business interests
  • Bank and savings accounts
  • Digital assets
  • Property acquired during marriage

Some of these assets may be controlled by a will or trust, while others can transfer through beneficiary designations, account agreements, or other arrangements.

This is why reviewing only your will may not be enough. Understanding the difference between probate and non-probate assets can help identify whether your entire financial picture still supports the plan you intended.

The People You Chose Years Ago May No Longer Be the Right Choice

Estate planning involves more than deciding who receives property.

Your documents may also name an executor, trustee, financial agent, or other individuals who could eventually have significant responsibilities. Someone who seemed like the natural choice ten years ago may no longer be the person you would choose today.

Relationships change. People move away, develop health problems, experience financial difficulties, or simply become less involved in your life.

During a review, consider whether:

  • Your executor is still willing and able to serve
  • Your trustee remains appropriate for the role
  • Your backup choices still make sense
  • Your beneficiaries reflect your current wishes
  • The people named in older documents are still part of your life

An estate plan can remain legally significant even when the relationships behind those decisions have changed. Periodic reviews help keep the documents connected to your current circumstances.

Planning for Children Changes as They Grow

Parents often create their first will when their children are young. At that stage, much of the planning may focus on guardianship and making sure someone can manage an inheritance for a minor child.

Those concerns can change significantly during your 40s.

Your children may be teenagers, approaching adulthood, or already beginning college or their careers. That does not necessarily mean they should receive a substantial inheritance outright as soon as they become adults.

A trust can provide more control over how and when assets are distributed. Depending on the family’s goals, it may allow assets to remain managed for a period of time rather than passing to a beneficiary all at once.

The appropriate structure depends on the family, the assets involved, and what parents want an inheritance to accomplish. This is one reason wills and trusts can serve different purposes within the same estate plan.

A Trust Created Years Ago May Need More Than a Quick Review

Creating a trust does not necessarily mean the planning process is finished.

Your assets may have changed considerably since the trust was prepared. You may have purchased another property, opened new financial accounts, changed investments, sold assets, or refinanced real estate.

That raises an important question: does the trust still coordinate with what you own today?

A review may include looking at:

  • Which assets are currently associated with the trust
  • Whether newly acquired property has been addressed
  • Whether trustee and successor trustee choices still make sense
  • Whether distribution instructions still reflect your goals
  • Whether beneficiary information remains current

A trust that no longer reflects your financial life may not accomplish everything you originally expected it to do.

For families who already have trusts, reviewing which assets should be placed in a trust can be an important part of keeping the overall plan coordinated.

Beneficiary Designations Deserve Their Own Review

Some of the largest assets people accumulate by their 40s may not be controlled directly by their wills.

Retirement plans, life insurance policies, and certain financial accounts can pass according to beneficiary designations. Those designations may have been completed years earlier and then forgotten, which is why it is important to review beneficiary designations periodically.

Reviewing them can be particularly important after:

  • Marriage or divorce
  • The birth or adoption of a child
  • The death of a beneficiary
  • A significant change in family relationships
  • Changing employers or retirement plans
  • Opening new investment or financial accounts

Beneficiary reviews are especially important for retirement accounts. The IRS recommends that plan participants review and potentially update retirement plan beneficiaries after major family changes such as marriage or having children 

An updated will does not necessarily correct an outdated beneficiary designation. Both parts of the plan need to be considered together.

This becomes particularly relevant with 401(k)s and other retirement accounts, where the way an account transfers can depend on how the account and beneficiary designation are structured.

Your 40s Are Also a Time to Think About Incapacity

Estate planning is not limited to deciding what happens after death.

An unexpected illness, accident, or other event could leave someone temporarily or permanently unable to manage financial or personal decisions. A complete review should therefore consider whether the plan addresses incapacity as well as inheritance.

That may involve reviewing documents and arrangements related to:

  • Financial decision-making
  • Medical decisions
  • Access to important information
  • Management of assets
  • Trust administration
  • Responsibilities for dependent family members

The people chosen for these responsibilities years ago may also need to be reconsidered.

Planning for incapacity becomes increasingly important as financial responsibilities grow because there may be more to manage if you are temporarily unable to handle those matters yourself.

Homeownership Can Change the Estate Planning Conversation

For many families, a home is one of their largest assets.

By your 40s, you may have accumulated substantial equity, purchased a second property, inherited real estate, or begun considering how a home should eventually pass to family members.

Real estate can raise questions that go beyond simply naming someone in a will. How property is titled and whether it is coordinated with a trust or another transfer strategy can affect what happens after death.

Families with multiple properties may have even more to consider, particularly when beneficiaries would otherwise inherit real estate together.

Reviewing your estate plan allows you to consider not only who should receive a property, but also how that transfer fits into the rest of the estate.

Your Financial Success May Have Changed What You Need

A plan created earlier in adulthood may have been designed when there were fewer assets to protect and fewer financial decisions to coordinate.

A decade later, the situation may be different.

Career growth, business ownership, investments, real estate appreciation, retirement savings, and other financial changes can increase the value and complexity of an estate without attracting much attention year to year.

This does not automatically mean everyone in their 40s needs a complicated trust structure. It does mean that planning decisions made when your financial life was simpler deserve another look.

A useful review asks whether the plan still fits the assets you have now, rather than the assets you had when the documents were signed.

A Review Does Not Always Mean Starting Over

Finding an older will or trust does not automatically mean every document needs to be replaced.

The purpose of a review is first to determine what still works and what may need attention. Depending on the circumstances, some documents may remain appropriate while others need to be updated.

Estate plans are commonly reviewed periodically and after major life changes because family circumstances, assets, and laws can change over time.

A review can focus on questions such as:

  • Do the documents still reflect your current family?
  • Are the right people named to handle important responsibilities?
  • Have your assets changed significantly?
  • Are beneficiary designations coordinated with the plan?
  • Does an existing trust still reflect what you own?
  • Have your goals for your beneficiaries changed?

The goal is not to change documents simply because you reached a particular birthday. It is to determine whether the plan created earlier in life still fits the life you have today.

Make Sure Your Estate Plan Has Grown With You

Your 40s can bring together responsibilities that did not exist when you first created a will or trust. Children may be growing up, assets may be increasing, careers may be advancing, and financial arrangements may be becoming more complex.

Your estate plan should keep pace with those changes.

At Henington Lewis Law Firm PLLC, we help individuals and families in Austin and Central Texas review wills, trusts, beneficiary arrangements, and other parts of their estate plans to determine whether they still reflect their current circumstances and long-term goals.

If your will or trust was created years ago, contact our firm to discuss whether your existing plan still works for the life and assets you have today.

Frequently Asked Questions

Should I update my will when I turn 40?

Turning 40 does not automatically mean you need a new will. However, your 40s are a useful time to review your existing documents because your family, assets, beneficiaries, and financial responsibilities may have changed significantly since the will was created.

How often should I review my will and trust?

There is no single schedule that works for everyone. A review every few years can help identify outdated information, but major life changes such as marriage, divorce, the birth of a child, a death in the family, or significant changes in assets may justify an earlier review.

Do I need to update my trust when I buy new property?

Not necessarily, but newly acquired property should be reviewed in connection with your trust. Depending on the type of trust, how the property is titled and whether it has been properly coordinated with the trust can affect how the asset is managed or transferred.

Should beneficiary designations be reviewed with my estate plan?

Yes. Retirement accounts, life insurance policies, and certain financial accounts may transfer according to their beneficiary designations rather than the instructions in a will. Reviewing these designations can help ensure they remain consistent with the rest of your estate plan.

What happens if my executor or trustee is no longer the right person?

Your estate planning documents may need to be updated if the person you selected is no longer willing, available, or appropriate to serve. It is also important to review any successor executors or trustees named in the documents.

Do I need a trust in my 40s?

Age alone does not determine whether you need a trust. Your assets, family circumstances, property ownership, goals for beneficiaries, and preferences for how assets should be managed or transferred are more important factors when deciding whether a trust makes sense.


Our Austin, TX Office Location

Joint Bank Accounts: Who Actually Inherits the Money?

Married couples and families often use joint bank accounts to share financial responsibilities. However, having two names on an account does not always mean the surviving account holder will automatically inherit the money when the other person dies.

In Texas, the outcome can depend on how the account holders set it up, whether it includes a right of survivorship, and what the account documents provide. Understanding these details can help determine whether the funds pass directly to another person or become part of the deceased account holder’s estate.

(512) 737-8404

Joint Bank Accounts Who Actually Inherits the Money

Joint Ownership Does Not Automatically Mean Survivorship

Seeing two names on a bank account can create the impression that each person automatically inherits the account when the other dies. But joint ownership and survivorship are not the same thing.

A joint account may allow more than one person to deposit, withdraw, or manage funds during their lifetimes. Those rights alone do not necessarily determine what happens to the money after one account holder dies.

In Texas, the outcome depends in part on whether the deceased account holder signed an agreement allowing their interest to pass to the surviving party. Simply labeling an account as “joint” or “joint tenancy” is not enough. Texas law requires a written survivorship agreement signed by the deceased account holder.

In practical terms, the names printed on a bank statement do not tell the entire story. The account documents matter.

The Right of Survivorship Changes What Happens at Death

When a joint account includes a valid right of survivorship, the surviving account holder may receive the remaining funds directly. The deceased owner’s interest may instead pass directly to the surviving account holder.

Consider a married couple who keeps savings in a joint account with a properly established right of survivorship. If one spouse dies, the account agreement may allow the surviving spouse to receive the funds without having that account distributed according to the deceased spouse’s will.

This makes survivorship an important part of determining which assets actually pass through probate. A will generally controls property that becomes part of the probate estate, but it does not necessarily override a valid arrangement that transfers an asset outside probate.

Understanding the difference between probate and non-probate assets can help families determine which property is actually available for distribution under a will.

When There Is No Right of Survivorship

The situation can become more complicated when multiple people are named on an account, but there is no valid survivorship agreement.

The surviving account holder should not assume that every dollar remaining in the account automatically belongs to them. Instead, the family or estate may need to determine the deceased person’s interest in the account and what should happen to that interest.

For example, a parent may add an adult child to help pay bills or manage finances.

  • How the account was originally established
  • Whether a survivorship agreement was signed
  • Who contributed money to the account
  • Whether the account arrangement changed over time
  • Why another person was added to the account
  • What the deceased owner’s estate planning documents provide

These questions are especially important when another person was added to an account for convenience. A parent, for example, may add an adult child so the child can help pay bills or manage finances. The parent may not have intended for that child to receive the entire balance after death.

Families should therefore review the purpose of the arrangement and the account documents rather than assume that access equals inheritance.

Access to the Account Is Not the Same as Inheritance

Someone may have written checks, made withdrawals, paid bills, or helped manage an account for years. After the original owner dies, that history of access can easily be mistaken for a right to inherit the remaining money.

Those are separate issues.

Someone’s authority during the account owner’s lifetime does not necessarily determine who owns the funds after death. This matters especially when an aging parent adds a child to an account for practical reasons.

What began as a convenient way to manage expenses may later create disagreement among siblings about whether the child was supposed to inherit the money or simply help manage it.

Before anyone withdraws or distributes substantial funds, the family should determine the type of account and review the rights created by its governing documents.

The Will and the Bank Account May Point in Different Directions

A joint account can create an unexpected result when its terms do not match what family members see in the will.

Suppose a parent’s will divides the estate equally among three children, but a substantial bank account also lists one child. If that account has a valid right of survivorship, the funds may pass directly to that child rather than being divided three ways under the will.

Other arrangements can also affect how property transfers after death, including:

  • Beneficiary designations
  • Trust ownership
  • Payable-on-death accounts
  • Retirement account beneficiaries
  • Life insurance beneficiaries
  • Survivorship provisions involving other assets

This is one reason families should not review a will in isolation. The ownership and beneficiary structure of individual assets can be just as important as the instructions contained in the will itself.

A coordinated estate plan considers how these different pieces work together.

Payable-on-Death Accounts Work Differently

Not every bank account that transfers outside probate is a joint account.

A payable-on-death account, often called a POD account, allows an account owner to designate someone to receive the funds after the owner dies. The beneficiary does not need to be a joint owner during the account owner’s lifetime. Texas law recognizes POD accounts as one of several multiple-party account arrangements that can affect how funds transfer after death. 

For families reviewing an estate, determining whether someone is a joint owner, survivorship owner, or POD beneficiary can help clarify whether the funds transfer directly or need to be addressed through probate.

Joint Accounts Can Create Unexpected Family Disputes

Disagreements often begin when the legal structure of an account does not match what different family members believe the deceased person intended.

The sibling who appears on the account may believe the parent intended them to receive the remaining balance. Other beneficiaries may expect the will to divide the money among them.

When questions arise, relevant information may include:

  • Account agreements and signature cards
  • Survivorship or beneficiary designations
  • Records showing who contributed the funds
  • Changes made to the account over time
  • The deceased person’s will or trust
  • Communications concerning why the account was created or changed

These disagreements can extend beyond ordinary estate administration when beneficiaries, heirs, executors, or account holders have competing claims to the funds.

Depending on the circumstances, questions about an account may become part of broader estate and inheritance disputes.

Review the Account Agreement, Not Just the Bank Statement

A bank statement can show whose names appear on an account, but it may not reveal all of the terms governing what happens after death.

The underlying account records can provide a clearer picture. Depending on the circumstances, useful documents may include:

  • The original account agreement
  • Signature cards
  • Right of survivorship designations
  • Payable-on-death designations
  • Documents showing later changes to the account
  • Records showing how the account was funded

The financial institution may also have records showing how the account holders set it up and whether they selected a survivorship or beneficiary arrangement.

These documents can become important during the probate process in Texas. They can help the executor or administrator determine which property belongs to the probate estate and which assets may transfer separately.

Coordinating Joint Accounts With Your Estate Plan

Joint accounts are not inherently a problem. They can make everyday financial management easier for married couples and allow a trusted family member to help someone who needs assistance managing expenses.

Problems are more likely when the account terms conflict with the rest of the estate plan.

Families should review joint accounts along with the rest of the estate plan, particularly after:

  • Marriage or divorce
  • The death of a spouse or another joint owner
  • Adding an adult child to help manage finances
  • A significant change in assets
  • Changes in family relationships
  • Creating or updating a will or trust

If you want the surviving account holder to receive the money, the account documents should reflect that intention. If you add someone only to help manage finances, you should also understand what rights the arrangement may create.

The goal is not simply to have a will. It is to make sure the different parts of the estate plan work together.

Understanding Who Is Entitled to the Account

The names on a joint bank account do not always reveal who will inherit the money in Texas.

A valid right of survivorship can allow funds to pass directly to a surviving account holder. A joint account without survivorship rights can produce a different result, while a POD designation creates another type of transfer altogether.

The account documents, ownership arrangement, and circumstances surrounding the account all matter.

At Henington Lewis Law Firm PLLC, we help individuals and families in Austin and Central Texas understand how bank accounts and other assets fit into their estate plans and how to address ownership after someone dies.

If you are planning your estate or have questions about a joint account after a death, contact our firm to discuss the next steps.

Frequently Asked Questions

Does a joint bank account automatically go to the surviving person in Texas?

No. Having two names on an account does not automatically mean the surviving account holder inherits all of the money. Whether the funds pass to the survivor can depend on the type of account and whether a valid right of survivorship was established.

What happens to a joint bank account when one owner dies in Texas?

It depends on how the account holders set it up. If the account includes a valid right of survivorship, the funds may pass directly to the surviving owner. Without survivorship rights, the deceased owner’s interest may need to be addressed through the estate.

Does a will override a joint bank account in Texas?

Not necessarily. If a joint account has a valid right of survivorship, the funds may transfer outside probate and may not be controlled by the terms of the deceased person’s will. This is why bank account designations should be coordinated with the overall estate plan.

What is the difference between a joint account and a payable-on-death account?

A joint account may give multiple owners rights to the account while they are alive. With a payable-on-death (POD) account, the designated beneficiary generally receives the funds after the account owner dies but does not have the same ownership rights during the owner’s lifetime.

Can a joint bank account become part of probate in Texas?

Yes, depending on how the account was structured. If the deceased owner’s interest does not pass through a valid survivorship or other non-probate arrangement, that interest may become part of the probate estate.

What documents should I check after a joint account owner dies?

Start with the account agreement and any documents showing how the account holders originally structured or later changed it. Signature cards, survivorship provisions, POD designations, and related bank records may help determine what happens to the funds after death.


Our Austin, TX Office Location

Lost or Missing Wills in Texas: What Families Need to Know

The family knows a will exists. Maybe someone remembers signing as a witness, the executor has an old copy, or an attorney prepared the document years ago. But when it is time to settle the estate, the original will is nowhere to be found.

That missing document can quickly change the direction of a Texas probate case.

The absence of an original will does not automatically mean the estate must be treated as if there were no will. Texas law provides a process for proving a will that cannot be produced in court. However, the person seeking to probate it may need to explain why the original cannot be located and provide sufficient evidence of what the will contained.

Lost or Missing Wills in Texas What Families Need to Know

The next steps depend heavily on what remains. A signed copy, information from the attorney who prepared the will, testimony from someone familiar with the document, or evidence that another person has the original can all become important.

Understanding how Texas handles a lost or missing will can help families protect the decedent’s wishes and determine the appropriate path through the probate process.

When an Original Will Cannot Be Located

An original will may disappear for many reasons. It may have been moved, misplaced among personal records, stored somewhere the family does not know about, or left with another person. In some cases, the family may find several estate planning documents but not the final signed will.

The reason the original is unavailable matters.

Under Texas Estates Code Section 256.156, a will that cannot be produced in court may still be proved. However, the person offering the will must provide evidence of the cause of its nonproduction that is sufficient to satisfy the court that it cannot be produced through reasonable diligence. The contents of the will must also be substantially proved.

This means a missing original creates a different probate issue than simply filing a will that is readily available.

Before deciding how the estate should proceed, families should determine what version of the will remains, when it was created, who may have seen it, and what efforts have already been made to locate the original.

Using a Copy of a Will During Texas Probate

Finding a copy can be significant because it provides evidence of the terms contained in the missing original. However, a photocopy is not simply substituted for the original without further consideration.

Texas law imposes additional proof requirements when the will itself cannot be produced in court. In addition to establishing why the original is unavailable, the contents of the will must be substantially proved through qualifying evidence. Current Texas law also specifically addresses copies that contain a copy of a self-proving affidavit.

The quality and completeness of the copy can therefore matter. A copy of the final signed document may provide considerably more information than an unsigned draft, notes about an estate plan, or an earlier version of the will.

Other evidence may also become relevant, including information from the attorney who prepared the estate plan and people who were familiar with the executed will.

Families should avoid assuming that any document labeled “will” represents the decedent’s final instructions. Establishing which document was actually executed and whether a later version existed may become part of the probate process.

Proving a Will When No Copy Exists

A case becomes more complicated when the original is missing and the family cannot locate a copy.

Texas law does not necessarily make the existence of a physical copy the only way to establish the contents of a will that cannot be produced. Depending on the available evidence, witness testimony may play an important role in substantially proving what the missing will contained.

That makes the history surrounding the estate plan particularly important.

The family may need to identify the attorney who prepared the documents, people who witnessed the will, individuals who saw the completed document, or records that help establish what was signed.

This is also where the distinction between knowing that someone intended to make a will and being able to establish an executed will and its contents becomes important. An unfinished draft or conversations about future plans do not necessarily establish the terms of a valid final will.

If the missing will ultimately cannot be established, the estate may need to proceed under Texas intestacy law instead.

Searching for the Original Will

A careful search should take place before concluding that the original has been lost.

Start with the places where the decedent kept other important records. A home safe, filing cabinet, desk, secure storage area, or safe-deposit arrangement may contain estate planning documents. Financial records, correspondence, or invoices may also identify the attorney or law firm that prepared the will.

Other estate documents can provide useful clues. A trust, power of attorney, advance directive, deed, or older will may contain an attorney’s name or indicate approximately when the estate plan was completed.

Family members should also consider whether the decedent gave the original to an executor, attorney, relative, or another trusted person for safekeeping.

This search should be organized rather than rushed. The firm’s recent guidance on what to do after someone dies in Texas emphasizes locating estate documents and understanding the estate before transferring property or making irreversible decisions.

Finding an older document should not automatically end the search. There may be a later will that revoked or replaced it.

When Another Person Has the Will

Sometimes the will is not actually lost. The family simply does not have possession of it.

A relative may have been given the original for safekeeping. The decedent may have left it with another trusted person. In other situations, family members may know who has the document but encounter resistance when trying to obtain it.

Texas law requires a person who has custody of a testator’s will, after receiving notice of the testator’s death, to deliver the will to the clerk of the court that has jurisdiction over the estate. 

That makes it important to distinguish between an original that genuinely cannot be located and one that may still be in another person’s possession.

A dispute over possession can also be an early indication of broader conflict. Family members may disagree about which will is valid, whether another version exists, or how the estate should be administered.

When those disagreements extend beyond locating the document, the matter may require more than routine probate administration and could involve probate litigation.

How a Missing Will Can Affect Probate

A missing will can add another layer of evidence and procedure to the administration of an estate.

Instead of presenting the original document and proceeding with the ordinary proof requirements, the applicant may also need to establish why the will cannot be produced and provide sufficient evidence of its contents. This can add additional procedural requirements to the probate case.

The situation can become more complicated when there are competing documents or conflicting accounts of the decedent’s wishes.

For example, one person may have a copy of a will while another believes a newer version was signed. Questions may arise about whether the available copy reflects the final estate plan, whether the original was revoked, or whether another person still possesses it.

These issues can affect how efficiently probate moves forward, particularly when beneficiaries or heirs disagree.

Families facing a missing will should therefore preserve copies, correspondence, attorney information, and other relevant records rather than discarding documents simply because they are not the original.

When the Estate May Proceed Without a Will

Not every search for a missing will ends with the document being admitted to probate.

If the will cannot be established under the applicable legal requirements, the probate estate may ultimately need to be administered without it. In that situation, Texas intestate succession law, rather than the instructions in the missing document, can determine who inherits probate property.

That difference can significantly change the outcome.

The beneficiaries someone intended to name in a will are not necessarily the same people who inherit under intestacy law. This can be particularly important for married couples, families with children from different relationships, unmarried partners, or anyone who intended to leave property to a friend, charity, or other beneficiary outside the statutory line of inheritance.

An Austin intestate succession lawyer can help determine inheritance rights when an estate must proceed without a valid will.

It is also important to remember that not every asset necessarily depends on the will. Property with beneficiary designations, survivorship rights, trust ownership, or other non-probate transfer mechanisms may pass separately from the probate estate. The distinction between probate and non-probate assets can therefore become especially important when a will is missing.

Preventing Problems With Your Own Will

A will can only carry out its intended purpose if the people responsible for your estate can locate it when the time comes.

That does not mean every family member needs a copy or access to your private estate planning documents. It does mean there should be a clear plan for where the original is stored and how the appropriate person can find it.

Your executor or another trusted person should know that a will exists and have enough information to locate it when necessary. If an attorney prepared your estate plan, keeping that attorney’s contact information with your important records can also make the process easier for your family.

Document management becomes particularly important after updating a will. Keeping outdated drafts and multiple unsigned versions without any organization can create unnecessary questions about which document represents your current wishes.

An Austin will attorney can help create or update a will and ensure it works together with the other components of your estate plan.

Moving Forward When a Will Is Missing

A missing original will does not have one automatic outcome.

A family may discover the original after a more thorough search. Another person may have custody of it. A copy and supporting evidence may allow the will to be presented through the process Texas provides for wills that cannot be produced. In other cases, the available evidence may not be sufficient and the estate may need to proceed differently.

The important first step is understanding what is actually missing and what evidence remains before treating the estate as though no will exists.

At Henington Lewis Law Firm PLLC, we help families in Austin and Central Texas evaluate probate matters involving missing wills, estate administration, beneficiaries, heirs, and disputes that can complicate the process.

If the original will cannot be located, contact our firm to discuss the circumstances and determine the appropriate next steps for the estate.

Frequently Asked Questions About Lost or Missing Wills in Texas

Can a copy of a will be probated in Texas?

Yes, in some circumstances. Texas law provides a process for proving a will that cannot be produced in court. Additional evidence may be required to explain why the original is unavailable and to substantially prove the contents of the will.

Does a lost original will become invalid in Texas?

Not automatically. The fact that the original cannot be located does not necessarily mean the will is invalid. Whether it can be admitted to probate depends on the circumstances and whether the requirements for proving a will that cannot be produced are satisfied.

What happens if there is no copy of the missing will?

The absence of a copy can make the process more difficult, but it does not necessarily end the matter. Texas law allows the contents of a missing will to be substantially proved through certain qualifying witness testimony. The available evidence will be important in determining whether the will can be established.

What happens if someone refuses to turn over the original will?

Texas law requires a person who has custody of a testator’s will, after receiving notice of the testator’s death, to deliver it to the clerk of the court with jurisdiction over the estate. Legal action may be necessary when someone who has the original refuses to provide it.

Can an estate go through probate if the will cannot be found?

Yes. The estate may still go through probate. If the missing will can be established under Texas law, it may be admitted to probate. If no valid will can ultimately be established, probate property may instead pass according to Texas intestate succession law.

How can I prevent my will from being lost?

Keep the original in a secure, accessible location, and make sure your executor or another trusted person knows how to find it when needed. When you update or replace your will, organize or properly address outdated versions so there is less confusion about which document reflects your current wishes.


Our Austin, TX Office Location

Probate vs. Non-Probate Assets: What’s the Difference?

A will is an important part of an estate plan, but it does not necessarily control everything you own. Some assets become part of your probate estate and may pass according to your will, while others transfer directly to a beneficiary or co-owner outside the probate process.

Understanding the difference between probate and non-probate assets can help you create a more coordinated estate plan, reduce confusion for your family, and avoid situations where an outdated beneficiary designation conflicts with your broader wishes.

Probate vs. Non-Probate Assets What’s the Difference

What Are Probate Assets?

Probate assets are generally assets owned in the deceased person’s individual name that do not have another legal method of transferring at death.

When probate is required, these assets become part of the estate administered by the executor or administrator.

Common examples may include:

  • Real estate owned solely by the deceased;
  • Bank accounts without a payable-on-death beneficiary;
  • Investment accounts without transfer-on-death instructions;
  • Vehicles titled only in the deceased person’s name;
  • Personal property such as jewelry, furniture, or collectibles; and
  • Certain business interests.

These assets may ultimately pass according to the will. If there is no valid will, Texas intestacy laws may determine who inherits them.

What Are Non-Probate Assets?

Non-probate assets transfer through another legal arrangement rather than through the will and probate estate.

The recipient is often determined by an account designation, ownership agreement, trust, or contract established before death.

Examples can include:

  • Life insurance with a named beneficiary;
  • Retirement accounts with beneficiary designations;
  • Payable-on-death bank accounts;
  • Transfer-on-death investment accounts;
  • Certain jointly owned property with survivorship rights;
  • Assets held in a trust; and
  • Property transferred through certain estate planning deeds.

Because these assets typically transfer outside probate, the instructions in a will generally do not override a valid beneficiary designation or survivorship arrangement.

Why Your Will Does Not Control Every Asset

One of the most common estate planning misunderstandings is assuming that a will determines who receives everything.

Consider a person whose will says that all property should be divided equally between two children. If a retirement account still names only one child as beneficiary, that account may pass entirely to the named beneficiary rather than being divided according to the will.

The same issue can occur with life insurance, POD accounts, jointly owned property, and other non-probate assets.

This is why an estate plan should coordinate the will with the way individual assets are titled and designated.

How Bank Accounts Can Transfer

A bank account can be either a probate or non-probate asset depending on how it is structured.

Individual Account Without a Beneficiary

An account owned solely by the deceased without a POD designation may become part of the probate estate.

Payable-on-Death Account

A POD account generally transfers directly to the named beneficiary after the account owner dies and the required documentation is provided.

Joint Account

A joint account may pass to a surviving owner if the account includes valid survivorship rights. Joint ownership alone does not always mean survivorship applies, so the account agreement matters.

The same type of asset can therefore receive very different treatment depending on how ownership was established.

What Happens to Real Estate?

Real estate is another area where ownership structure matters.

A home owned solely by the deceased may become a probate asset unless another transfer mechanism applies.

Property may pass differently when it is:

  • Owned with valid survivorship rights;
  • Properly transferred into a trust;
  • Subject to a valid transfer-on-death deed or other planning arrangement; or
  • Owned through an entity or other structure.

Reviewing deeds and ownership records is essential when determining whether real estate must pass through probate.

Retirement Accounts and Life Insurance

Retirement accounts and life insurance commonly pass through beneficiary designations.

These assets may include:

  • 401(k) accounts;
  • IRAs;
  • Employer retirement plans;
  • Pension benefits; and
  • Life insurance policies.

When a valid beneficiary is named, the proceeds generally transfer directly to that person rather than through the will.

This makes beneficiary reviews an important part of estate planning. A designation made many years ago may no longer reflect the account owner’s current wishes.

What Happens When a Beneficiary Dies First?

Problems can arise when a named beneficiary dies before the account owner and the designation is never updated.

What happens next depends on the account terms and whether a contingent beneficiary was named.

The asset might:

  • Pass to a contingent beneficiary;
  • Become payable to the account owner’s estate; or
  • Transfer according to the institution’s default rules.

If the asset becomes payable to the estate, it may then become subject to probate.

Naming and periodically reviewing contingent beneficiaries can help reduce this risk.

Assets Held in a Trust

Assets properly transferred into a trust are generally managed according to the trust agreement rather than the will.

After the trust creator dies, a successor trustee may take responsibility for administering the trust and distributing property according to its terms.

However, creating a trust document alone is not enough.

Assets that were supposed to be placed in the trust but were never properly retitled may still become probate assets. This is why trust funding is an important part of creating a complete trust-based estate plan.

Business Interests Can Require Additional Planning

Business ownership does not always transfer simply through a will.

Operating agreements, partnership agreements, shareholder agreements, buy-sell arrangements, or other contracts may determine what happens to an ownership interest after death.

A business owner’s estate plan should coordinate these agreements with:

  • The will;
  • Trusts;
  • Beneficiary arrangements;
  • Business succession planning; and
  • Other ownership documents.

Conflicting instructions can create uncertainty for family members and business partners.

What Happens If There Is No Will?

If someone dies without a valid will, probate assets may pass according to Texas intestacy laws.

Non-probate assets generally continue to transfer according to their own beneficiary, ownership, or contractual arrangements.

For example, a life insurance policy with a valid beneficiary does not normally become subject to intestacy simply because the policyholder did not have a will.

This distinction makes asset ownership important even for someone without a formal estate plan.

Can Non-Probate Assets Still Create Estate Problems?

Yes.

Avoiding probate does not automatically mean an asset fits correctly into the estate plan.

Problems may arise when:

  • A former spouse remains named as beneficiary;
  • One child receives a large non-probate account while the will divides other assets equally;
  • A beneficiary dies and no contingent beneficiary is named;
  • An account designation conflicts with the family’s understanding of the estate plan; or
  • Assets intended for a trust were never transferred into it.

These issues can create unintended distributions and family disagreements even when the legal transfer itself is straightforward.

Coordinating Probate and Non-Probate Assets

A comprehensive estate plan should consider both categories together.

That means reviewing:

  • Wills;
  • Trusts;
  • Bank accounts;
  • Investment accounts;
  • Retirement plans;
  • Life insurance;
  • Real estate ownership;
  • Business interests; and
  • Beneficiary designations.

The goal is not necessarily to make every asset probate or every asset non-probate. Instead, the goal is to make sure each asset transfers in a way that supports the overall estate plan.

When Should Beneficiary Designations Be Reviewed?

Reviewing beneficiary designations can be especially important after:

  • Marriage;
  • Divorce;
  • The birth or adoption of a child;
  • The death of a beneficiary;
  • A major change in assets;
  • Retirement;
  • Creating or updating a trust; or
  • Significant changes in family relationships.

Periodic reviews can also catch outdated information before it creates a problem.

Probate Avoidance Is Not the Only Goal

Avoiding probate can be useful in many estate plans, but it should not be the only consideration.

An asset transfer strategy should also account for:

  • Who should receive the property;
  • When they should receive it;
  • Whether protection or management is needed;
  • Tax and financial considerations;
  • Family circumstances; and
  • How the transfer fits with the rest of the estate plan.

A direct beneficiary designation may be simple, but a trust may offer greater control for certain beneficiaries or assets.

Make Sure Your Estate Plan and Your Assets Tell the Same Story

A well-written will is only one part of determining what happens to your property after death.

If beneficiary designations, account ownership, deeds, trusts, and business agreements point in different directions, your assets may not transfer the way you expect.

At Henington Lewis Law Firm PLLC, we help Texas families coordinate wills, trusts, beneficiary designations, property ownership, and other estate planning tools so they work together. Reviewing how your assets are structured today can help prevent confusion and ensure your estate plan better reflects your wishes when the time comes.

Frequently Asked Questions

What is the difference between probate and non-probate assets?

Probate assets pass through estate administration, while non-probate assets generally transfer directly through a beneficiary designation, trust, or ownership arrangement.

Does a will control non-probate assets?

Generally, no. Valid beneficiary designations and survivorship arrangements usually determine how non-probate assets transfer.

Are bank accounts probate assets?

They can be. An individually owned account without a POD beneficiary may require probate, while a valid POD account may transfer directly.

Is life insurance a probate asset?

Usually not when a valid beneficiary is named. If the estate is the beneficiary, the proceeds may become part of the probate estate.

Are assets in a trust subject to probate?

Assets properly transferred into a trust generally avoid probate and are administered according to the trust terms.

What happens to probate assets if there is no will?

They generally pass according to Texas intestacy laws when there is no valid will.


Our Austin, TX Office Location

Can You Disinherit a Child or Family Member in Texas?

Disinheriting a child or another family member is a serious estate planning decision. In Texas, you generally have broad freedom to decide who should receive your property after death, but the way you express that decision matters. A poorly drafted will or unclear estate plan can create confusion, increase the risk of a contest, and lead to disputes among surviving family members.

For that reason, disinheritance should be handled carefully. The goal is not only to state who will not inherit, but also to make sure the rest of the estate plan clearly reflects your wishes and complies with Texas law.

Can You Disinherit a Child or Family Member in Texas

Can You Disinherit a Child in Texas?

In many situations, yes. Texas law generally allows a parent to leave a child out of a will or trust.

However, simply omitting a child’s name can create uncertainty about whether the omission was intentional or accidental. A carefully drafted estate plan should make your intent clear so there is less room for disagreement later.

Disinheritance can also become more complicated when the child is a minor, financially dependent, disabled, or connected to assets that pass outside the will.

Can You Disinherit Other Family Members?

You can generally choose not to leave property to adult children, siblings, parents, extended relatives, or other family members.

Marriage is different. A surviving spouse may have certain property and homestead rights under Texas law that cannot always be eliminated simply by leaving the spouse out of a will.

This is one reason estate planning should consider more than just the language in the will itself. Property ownership, beneficiary designations, marital property rules, trusts, and other legal rights can all affect what happens after death.

Why Someone Might Choose to Disinherit a Family Member

Families make this decision for many different reasons.

Some common situations include:

  • A long-term estrangement;
  • A beneficiary who has already received significant financial support;
  • Concerns about addiction or financial mismanagement;
  • A desire to leave more property to another child with greater needs;
  • Family conflict;
  • A beneficiary who is financially independent;
  • A decision to leave assets to charity instead; or
  • Concerns that an inheritance could create additional financial or personal problems.

The reason does not necessarily need to appear in the estate plan. In some cases, providing too much explanation can create more opportunities for conflict.

Should You Mention the Disinherited Person in Your Will?

Often, clearly acknowledging the person can help show that the omission was intentional.

For example, an estate plan may state that the person intentionally receives no inheritance under the will.

This can help distinguish intentional disinheritance from an accidental omission.

However, the wording should be carefully considered. Detailed accusations, emotional statements, or explanations about family conflict may create unnecessary tension and potentially become evidence in later litigation.

Clear and neutral language is usually more effective.

What Happens If You Simply Leave Someone Out?

Leaving a family member out without explanation can create uncertainty.

A beneficiary or heir may argue that:

  • The omission was accidental;
  • The will does not reflect the deceased person’s true wishes;
  • A later document is missing;
  • Someone exercised undue influence; or
  • The person lacked the mental capacity to make the estate plan.

These claims are not automatically successful, but ambiguity can make an estate dispute more likely.

A properly drafted estate plan can reduce that uncertainty.

Can a Disinherited Child Contest the Will?

Being disinherited does not automatically give someone the right to overturn a will. However, an interested person may challenge the validity of the document when legal grounds exist.

Potential grounds for a will contest can include:

  • Lack of testamentary capacity;
  • Undue influence;
  • Fraud;
  • Forgery;
  • Improper execution; or
  • Questions about whether the document is the valid final will.

A child who is simply unhappy with the inheritance decision generally needs more than disagreement to invalidate a valid estate plan.

Reducing the Risk of a Will Contest

No estate plan can guarantee that a disappointed family member will never challenge it, but thoughtful planning can make the creator’s intentions much clearer.

Strategies may include:

  • Using clear language;
  • Following all Texas execution requirements;
  • Updating outdated documents;
  • Avoiding last-minute changes when possible;
  • Documenting mental capacity when appropriate;
  • Selecting trustworthy witnesses;
  • Keeping estate planning documents organized; and
  • Working with an attorney when significant family conflict exists.

Consistency across the estate plan also matters. A will, trust, beneficiary designation, and property ownership arrangement should not unintentionally contradict one another.

Using a Trust When Family Conflict Is a Concern

A trust can sometimes provide more control than an outright inheritance under a will.

Depending on the family’s goals, a trust may allow assets to be:

  • Managed over time;
  • Distributed under specific conditions;
  • Protected for younger beneficiaries;
  • Controlled by an independent trustee; or
  • Preserved for future generations.

Trust planning may also provide more privacy because assets properly held in a trust may avoid certain aspects of the probate process.

However, a trust does not automatically prevent disputes. The document still needs to be clearly drafted and properly funded.

Disinheritance Is Different From Leaving a Smaller Share

Estate planning does not have to be all or nothing.

Instead of completely disinheriting someone, you may decide to:

  • Leave them a smaller percentage;
  • Give them a specific asset;
  • Provide an inheritance through a trust;
  • Delay distributions;
  • Limit access to principal; or
  • Direct the majority of the estate to other beneficiaries.

These options can sometimes better reflect family circumstances while still addressing concerns about a particular beneficiary.

Be Careful With Beneficiary Designations

A will does not control every asset.

Life insurance, retirement accounts, payable-on-death accounts, transfer-on-death accounts, and certain jointly owned property may pass according to beneficiary designations or ownership arrangements.

That means a person you removed from your will could still receive significant assets if older beneficiary designations remain in place.

When changing who should inherit, review the entire estate plan rather than focusing only on the will.

Consider the Impact on Minor or Dependent Children

Disinheritance involving a minor child or dependent family member can raise additional concerns.

A parent may still need to think about:

  • Guardianship;
  • Financial support;
  • Trust planning;
  • Special needs;
  • Education expenses; and
  • Other long-term care needs.

A plan designed for an independent adult beneficiary may not be appropriate for someone who depends financially or medically on the person creating the estate plan.

Special Needs Beneficiaries Require Careful Planning

Completely excluding a beneficiary with disabilities may not always be the best way to protect them.

In some situations, a properly structured special needs trust can provide financial support while helping preserve eligibility for certain government benefits.

This allows the estate plan to address the beneficiary’s needs without necessarily giving them an unrestricted inheritance.

The appropriate strategy depends on the beneficiary’s circumstances and the benefits they receive.

Review the Plan After Family Changes

A decision to disinherit someone should not necessarily remain unchanged forever.

Review the estate plan after events such as:

  • Marriage or divorce;
  • Reconciliation with a family member;
  • The birth of children or grandchildren;
  • A significant change in wealth;
  • A beneficiary’s death;
  • Changes in health;
  • Changes in family relationships; or
  • Major property acquisitions.

An estate plan should reflect current intentions, not circumstances from many years earlier.

Communication May Help, but It Is Not Always Appropriate

Some families choose to explain inheritance decisions before death. Others prefer to keep the plan private.

No single approach works for every family.

A conversation may reduce surprise and conflict in some situations. In others, discussing the decision could worsen an already difficult relationship.

The estate plan itself should be strong enough to communicate the legal intent regardless of whether the family discusses it beforehand.

Creating a Clear Estate Plan Matters

Disinheriting a child or family member involves more than removing a name from a document.

A strong estate plan should clearly identify who will receive property, coordinate wills and trusts with beneficiary designations, account for Texas property rules, and reduce ambiguity about the creator’s intentions.

At Henington Lewis Law Firm PLLC, we help Texas families create and update estate plans that reflect their individual circumstances, including situations involving estrangement, unequal inheritances, blended families, beneficiary concerns, and potential estate disputes. Thoughtful planning can help make your wishes clearer and reduce the risk of unnecessary conflict later.

Frequently Asked Questions

Can you legally disinherit a child in Texas?

Yes. In many cases, a parent can intentionally leave an adult child out of a will or trust.

Can a disinherited child contest a will?

Yes, but they generally need legal grounds such as undue influence, fraud, lack of capacity, or improper execution.

Can you disinherit a spouse in Texas?

Not always completely. A surviving spouse may still have certain property and homestead rights under Texas law.

Should you mention a disinherited child in your will?

Often, yes. Clearly stating that the omission is intentional can help reduce confusion about your wishes.

Does a will control all inherited assets?

No. Life insurance, retirement accounts, POD accounts, trusts, and certain jointly owned assets may transfer outside the will.

Can a trust help reduce inheritance disputes?

Yes. A properly structured trust can provide clearer distribution rules, greater control, and additional privacy.


Our Austin, TX Office Location

What Happens to Bank Accounts After Someone Dies?

When someone dies, their bank accounts do not all follow the same process. What happens next depends on how the account is titled, whether a beneficiary is named, whether another person is a joint owner, and whether the account becomes part of the probate estate.

For families, this can be confusing because access to a deceased person’s bank account may suddenly be restricted. Understanding the different ways accounts transfer can help prevent mistakes and make estate administration easier.

What Happens to Bank Accounts After Someone Dies

What Happens to a Bank Account When the Owner Dies?

After a bank learns that an account holder has died, it may restrict access to the account until it receives the documents needed to determine who has legal authority.

The bank may request:

  • A certified death certificate;
  • Identification from the person requesting access;
  • Probate documents showing who has authority to act for the estate;
  • Beneficiary information; or
  • Documentation showing joint ownership or survivorship rights.

What happens next depends largely on how the account was structured before death.

Joint Bank Accounts May Transfer Differently

A joint account does not always become part of the deceased person’s probate estate.

If the account includes a valid right of survivorship, the surviving owner may be entitled to continue using the account after the other owner dies.

However, simply having two names on an account does not always answer every ownership question. The account agreement and the form of ownership matter.

Families should avoid assuming that a joint account automatically belongs entirely to the surviving owner without reviewing how the account was established.

Payable-on-Death Accounts Can Pass Outside Probate

A payable-on-death, or POD, designation allows an account owner to name someone who should receive the funds after death.

When the account owner dies, the named beneficiary may generally claim the account directly from the financial institution after providing the required documentation.

Because the account transfers through the beneficiary designation, it may avoid becoming part of the probate estate.

This can simplify the transfer process, but it also means the POD designation may control even if the will says something different.

Accounts Without a Beneficiary May Become Probate Assets

If a bank account is owned solely by the deceased person and does not have a valid beneficiary or survivorship arrangement, it may become part of the probate estate.

In that situation, the executor or administrator may need legal authority from the probate court before the bank releases the funds.

The money may then be used to:

  • Pay estate expenses;
  • Address valid creditor claims;
  • Pay taxes;
  • Cover administration costs; and
  • Make distributions to beneficiaries or heirs.

The account does not automatically belong to the person named in the will until the estate process is properly completed.

Can an Executor Access a Deceased Person’s Bank Account?

Not immediately in every case.

Being named as executor in a will does not always give someone instant authority over the deceased person’s accounts. If probate is required, the executor generally must receive formal authority from the court before acting on behalf of the estate.

Once appointed, the executor may be able to:

  • Obtain account information;
  • Collect estate funds;
  • Transfer money into an estate account;
  • Pay valid expenses; and
  • Keep records of estate transactions.

The bank may require court-issued documentation before providing access.

What Is an Estate Bank Account?

An estate bank account is a separate account opened to manage money belonging to the probate estate.

After an executor or administrator receives authority, funds from the deceased person’s probate accounts may be transferred into the estate account.

The executor can then use that account to manage:

  • Funeral or estate expenses;
  • Property costs;
  • Taxes;
  • Creditor payments;
  • Professional fees; and
  • Final beneficiary distributions.

Using a separate estate account can make recordkeeping clearer and reduce the risk of mixing estate money with personal funds.

What Happens to Automatic Payments and Deposits?

Bank accounts may still have activity after the account holder dies.

Automatic payments might include:

  • Mortgage payments;
  • Utilities;
  • Insurance premiums;
  • Subscription services; and
  • Loan payments.

There may also be incoming deposits, such as refunds, payments, or benefits.

Families should review account activity carefully rather than immediately closing every account. Some expenses may need to continue temporarily to protect estate property.

At the same time, payments that are no longer appropriate should be identified and addressed.

What Happens to Direct Deposits After Death?

Certain payments may need to stop after death.

For example, government benefits, pension payments, or other recurring deposits may have specific rules about payments issued after the recipient dies.

If funds are deposited after death and the recipient was not entitled to receive them, the institution or agency may require repayment.

This is another reason why reviewing account activity promptly is important.

Can Family Members Withdraw Money After Someone Dies?

Family members generally should not withdraw money simply because they know the account information or previously had access.

Using a deceased person’s debit card, online banking credentials, checks, or account funds without proper authority can create legal and financial complications.

Even when the money will eventually pass to a family member, the estate may first need to address debts, taxes, expenses, or other obligations.

It is safer to determine who has legal authority before moving estate funds.

What If Someone Was an Authorized User or Had Power of Attorney?

Authority that existed during the account holder’s lifetime may not continue after death.

A power of attorney is generally intended to allow someone to act for another person while that person is alive. Once the principal dies, the authority under that document typically ends.

Similarly, being an authorized user or having access to online banking does not necessarily mean the person has ownership rights after death.

After death, authority usually depends on beneficiary status, joint ownership, trust arrangements, or probate authority.

What Happens If the Account Is Held in a Trust?

If a bank account is properly titled in the name of a trust, it may be managed according to the trust terms rather than through probate.

After the trust creator dies, the successor trustee may take over management of the trust account.

The trustee may then use the funds according to the trust agreement, including paying appropriate expenses and making distributions to beneficiaries.

Proper titling is important. Creating a trust alone does not automatically move a bank account into it.

Can Creditors Access Money in a Deceased Person’s Bank Account?

If the account becomes part of the probate estate, estate funds may be available to pay valid debts before beneficiaries receive distributions.

The executor or administrator must follow the appropriate process for handling creditor claims.

This is why beneficiaries should not assume that the full account balance will be distributed immediately.

The estate may need to address:

  • Credit cards;
  • Medical bills;
  • Taxes;
  • Loans;
  • Funeral expenses; and
  • Other valid obligations.

How Long Does It Take to Access a Deceased Person’s Bank Account?

There is no single timeline.

A POD account may transfer relatively quickly once the beneficiary provides the required documents. A joint account with survivorship rights may also be easier to access.

A probate account may take longer because the executor or administrator may first need court authority.

The timeline can also depend on:

  • Whether there is a valid will;
  • Whether probate is contested;
  • The bank’s procedures;
  • The type of account; and
  • Whether ownership or beneficiary questions exist.

Common Mistakes Families Should Avoid

Bank accounts can create problems when families act before understanding how ownership works.

Common mistakes include:

  • Withdrawing money without authority;
  • Using the deceased person’s debit card;
  • Closing accounts too quickly;
  • Ignoring automatic payments;
  • Assuming the will controls every account;
  • Mixing estate funds with personal money; and
  • Failing to keep records of estate transactions.

Taking the time to understand how each account is structured can prevent unnecessary disputes and accounting problems later.

When Should You Contact a Probate Attorney?

Legal guidance can be especially helpful when:

  • The bank refuses to release information;
  • No beneficiary is listed;
  • Multiple family members claim the account;
  • A joint account creates an ownership dispute;
  • Someone has withdrawn money without authority;
  • Probate has not yet been opened;
  • The executor is unsure how to handle estate funds; or
  • Creditor claims may affect the account.

An attorney can help determine whether the account belongs to the probate estate and what legal steps are necessary to access or distribute the funds.

Understanding the Account Structure Comes First

What happens to a bank account after someone dies depends on how the account was set up before death.

A POD beneficiary, surviving joint owner, trustee, executor, or administrator may each have different rights depending on the circumstances. Before moving money or closing accounts, families should first determine who legally owns the funds and who has authority to act.

At Henington Lewis Law Firm PLLC, we help Texas families navigate probate, estate administration, and questions involving bank accounts and other estate assets. Whether you are an executor trying to access estate funds or a beneficiary trying to understand how an account should transfer, our team can help clarify the next steps.

Frequently Asked Questions

Can a bank freeze an account after someone dies?

Yes. A bank may restrict access until it receives the documents needed to determine who has legal authority.

Does a joint bank account automatically go to the surviving owner?

Not always. It depends on how the account is titled and whether survivorship rights apply.

Do payable-on-death accounts go through probate?

Usually not. A valid POD beneficiary can often claim the funds directly from the bank.

Can an executor use money from a deceased person’s bank account?

Only after receiving proper authority and following the rules for managing estate funds.

Does power of attorney still work after death?

Generally, no. A power of attorney typically ends when the person who granted it dies.

What happens to a bank account with no beneficiary?

If no beneficiary or survivorship arrangement applies, the account may become part of the probate estate.


Our Austin, TX Office Location

Planning for Incapacity: Who Will Manage Your Finances and Healthcare?

Estate planning is not only about what happens after death. It should also address what happens if an illness, injury, or cognitive decline leaves you unable to manage your finances or make healthcare decisions on your own.

Without a plan, family members may be unsure who has authority to pay bills, access accounts, manage property, speak with doctors, or make medical decisions. In some cases, they may need court involvement before they can act. Planning for incapacity helps create clear instructions and gives trusted people the legal authority they may need.

Planning for Incapacity

What Does Incapacity Mean in Estate Planning?

Incapacity generally refers to a situation where a person can no longer make or communicate certain decisions independently.

This may result from:

  • A serious illness;
  • An accident or injury;
  • Dementia or cognitive decline;
  • A stroke;
  • Complications from surgery; or
  • Another condition that affects decision-making ability.

Incapacity can be temporary or permanent. Because it is often unpredictable, planning ahead can help avoid uncertainty during an already difficult situation.

Who Will Manage Your Finances If You Cannot?

If you become unable to handle your financial affairs, someone may need authority to manage tasks such as:

  • Paying household expenses;
  • Managing bank accounts;
  • Handling investments;
  • Paying taxes;
  • Managing real estate;
  • Maintaining insurance;
  • Operating a business; and
  • Addressing debts and other financial obligations.

Simply being a spouse, child, or close relative does not always give someone automatic authority to manage every account or financial matter.

That authority usually needs to come from an appropriate legal document or another recognized legal arrangement.

Using a Financial Power of Attorney

A financial power of attorney allows you to appoint someone, often called an agent, to handle financial and legal matters on your behalf.

Depending on how the document is drafted, the agent may have authority to:

  • Access and manage bank accounts;
  • Pay bills;
  • Handle real estate transactions;
  • Manage investments;
  • File taxes;
  • Deal with insurance matters; and
  • Address certain business or legal issues.

A durable power of attorney is especially important for incapacity planning because it can remain effective even if you later become unable to make decisions for yourself.

Choosing the right agent matters. The person should be trustworthy, organized, financially responsible, and willing to follow your instructions.

How a Revocable Living Trust Can Help

For some families, a revocable living trust can provide another layer of continuity.

While you are able to manage your own affairs, you may serve as trustee and control the assets held in the trust. If you later become incapacitated, a successor trustee can step in and manage trust property according to the terms of the trust.

This can be especially helpful for:

  • Real estate;
  • Investment accounts;
  • Business interests;
  • Multiple properties; and
  • Other assets that require ongoing management.

A trust does not replace every incapacity planning document, but it can work alongside powers of attorney and healthcare directives to create a more complete plan.

Who Will Make Healthcare Decisions for You?

Financial planning is only part of incapacity planning. You should also decide who will make medical decisions if you cannot communicate or provide informed consent.

A medical power of attorney allows you to appoint someone to make healthcare decisions on your behalf when you are unable to make those decisions yourself.

The person you choose may need to:

  • Speak with doctors;
  • Review treatment options;
  • Consent to or refuse certain procedures;
  • Make decisions about rehabilitation or long-term care; and
  • Communicate your wishes to healthcare providers and family members.

Choose someone who understands your values, can handle difficult conversations, and is willing to advocate for your preferences.

Advance Directives Can Clarify Your Wishes

An advance directive, sometimes called a living will, can provide instructions about certain medical treatments if you develop a terminal or irreversible condition and cannot communicate your wishes.

This document can address decisions involving life-sustaining treatment and other end-of-life care preferences.

Putting those wishes in writing can reduce uncertainty for both family members and healthcare providers.

It can also help prevent loved ones from having to make difficult decisions without knowing what you would have wanted.

HIPAA Authorization and Access to Medical Information

Even when someone is closely involved in your care, privacy laws may limit access to your medical information.

A HIPAA authorization can allow designated individuals to receive protected health information from doctors, hospitals, and other healthcare providers.

This can be important when family members need to understand your condition, coordinate care, or communicate with medical professionals.

Without proper authorization, even trusted relatives may encounter delays or restrictions when trying to obtain information.

What Happens Without an Incapacity Plan?

When no valid planning documents are in place, families may face significant obstacles.

Depending on the circumstances, someone may need to ask a court to appoint a guardian or take other legal steps before they can manage finances or make certain decisions.

Court proceedings can add:

  • Time;
  • Expense;
  • Public filings;
  • Ongoing supervision; and
  • Stress for family members.

Planning in advance can reduce the likelihood that a court will need to decide who should manage your affairs.

Choosing the Right Decision-Makers

The people you select are just as important as the documents themselves.

When choosing agents, successor trustees, or healthcare decision-makers, consider:

  • Trustworthiness;
  • Financial responsibility;
  • Ability to remain calm under pressure;
  • Willingness to communicate with family members;
  • Familiarity with your wishes;
  • Geographic availability; and
  • Ability to handle complex decisions.

You may also want to name backup decision-makers in case your first choice is unavailable or unwilling to serve.

Keep Financial and Medical Information Organized

Legal authority is much more useful when the person acting on your behalf can find the information they need.

Consider keeping an organized record of:

  • Bank and investment accounts;
  • Insurance policies;
  • Real estate documents;
  • Business records;
  • Important contacts;
  • Medications and healthcare providers;
  • Estate planning documents; and
  • Instructions for accessing important digital information.

You do not necessarily need to give everyone immediate access to sensitive information, but trusted people should know where important documents are located and whom to contact if something happens.

When Should You Update an Incapacity Plan?

Incapacity planning should not be a one-time task.

Review your documents after major changes such as:

  • Marriage or divorce;
  • The death or incapacity of an appointed agent;
  • Moving;
  • Starting or selling a business;
  • Significant changes in assets;
  • Changes in family relationships; or
  • A new medical diagnosis.

You should also review your plan periodically to confirm that the people you selected are still appropriate and that your documents reflect your current wishes.

Planning Before a Crisis Gives You More Control

The best time to plan for incapacity is while you are healthy and able to make your own decisions.

Waiting until a medical emergency occurs can limit your options and place more responsibility on family members who may already be under significant stress.

A well-designed incapacity plan can help ensure that:

  • Someone you trust can manage your financial affairs;
  • Your healthcare decisions reflect your preferences;
  • Important assets continue to be managed;
  • Your family knows who has authority to act; and
  • Court involvement may be reduced or avoided.

Protecting Your Independence Through Planning

Incapacity planning is ultimately about maintaining control over your affairs even when you cannot manage them personally.

By choosing trusted decision-makers and preparing the right legal documents in advance, you can provide clear guidance for your family and reduce uncertainty during difficult circumstances.

At Henington Lewis Law Firm PLLC, we help Texas families create estate plans that address both lifetime decision-making and long-term legacy goals. Whether you need powers of attorney, healthcare directives, trust planning, or a broader estate plan, our team can help you build a strategy designed around your needs and priorities.

Frequently Asked Questions

What is incapacity planning?

Incapacity planning prepares for who will manage your finances and healthcare if you become unable to make decisions yourself.

What documents are used for incapacity planning?

Common documents include a durable power of attorney, medical power of attorney, advance directive, HIPAA authorization, and sometimes a trust.

Does a spouse automatically have financial authority?

Not always. A spouse may still need legal authority to manage certain accounts, property, or financial matters.

What happens if I become incapacitated without a power of attorney?

Your family may need to seek court involvement before someone can legally manage certain financial or personal matters.

Can a trust help during incapacity?

Yes. A successor trustee may be able to manage assets held in the trust if you become unable to do so.

How often should incapacity documents be updated?

Review them after major life changes and periodically to make sure your decision-makers and instructions still reflect your wishes.


Our Austin, TX Office Location

Whether you need a personalized estate plan or help handling a civil dispute, we're here to help

Take the first step toward protecting your legacy and giving your family lasting peace of mind. Whether you need a personalized estate plan or help handling a civil dispute, we're here to help.

Contact Us

Send us a message and we'll reach out to schedule a consultation.