Joint Bank Accounts: Who Actually Inherits the Money?
Married couples and families often use joint bank accounts to share financial responsibilities. However, having two names on an account does not always mean the surviving account holder will automatically inherit the money when the other person dies.
In Texas, the outcome can depend on how the account holders set it up, whether it includes a right of survivorship, and what the account documents provide. Understanding these details can help determine whether the funds pass directly to another person or become part of the deceased account holder’s estate.
Joint Ownership Does Not Automatically Mean Survivorship
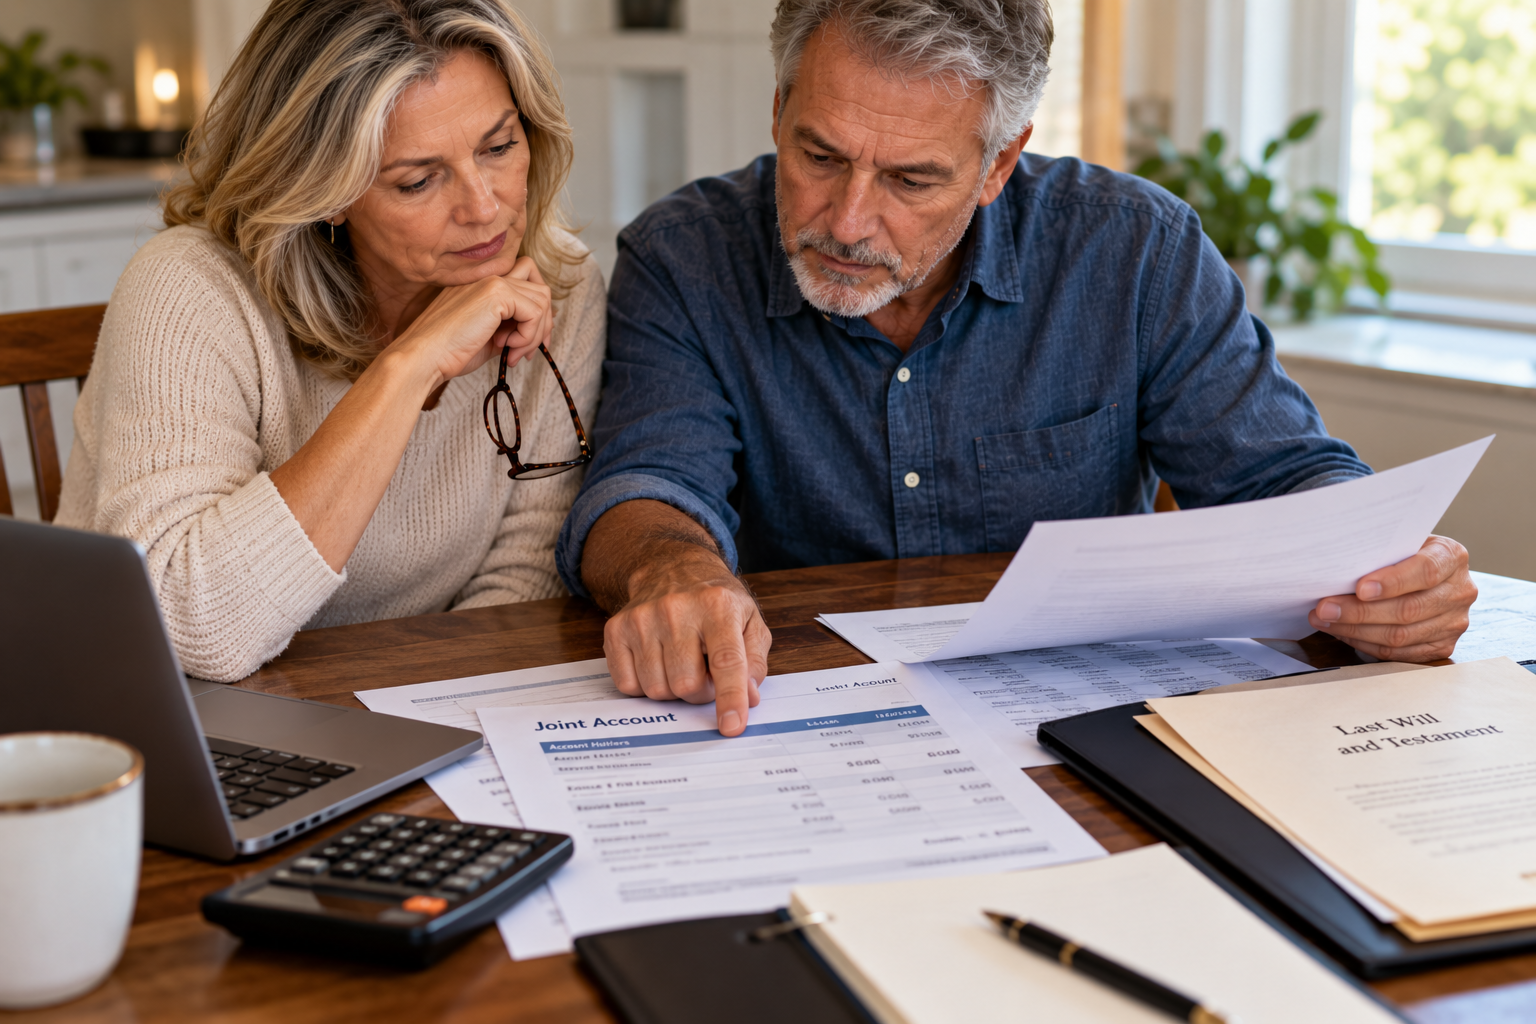
Seeing two names on a bank account can create the impression that each person automatically inherits the account when the other dies. But joint ownership and survivorship are not the same thing.
A joint account may allow more than one person to deposit, withdraw, or manage funds during their lifetimes. Those rights alone do not necessarily determine what happens to the money after one account holder dies.
In Texas, the outcome depends in part on whether the deceased account holder signed an agreement allowing their interest to pass to the surviving party. Simply labeling an account as “joint” or “joint tenancy” is not enough. Texas law requires a written survivorship agreement signed by the deceased account holder.
In practical terms, the names printed on a bank statement do not tell the entire story. The account documents matter.
The Right of Survivorship Changes What Happens at Death
When a joint account includes a valid right of survivorship, the surviving account holder may receive the remaining funds directly. The deceased owner’s interest may instead pass directly to the surviving account holder.
Consider a married couple who keeps savings in a joint account with a properly established right of survivorship. If one spouse dies, the account agreement may allow the surviving spouse to receive the funds without having that account distributed according to the deceased spouse’s will.
This makes survivorship an important part of determining which assets actually pass through probate. A will generally controls property that becomes part of the probate estate, but it does not necessarily override a valid arrangement that transfers an asset outside probate.
Understanding the difference between probate and non-probate assets can help families determine which property is actually available for distribution under a will.
When There Is No Right of Survivorship
The situation can become more complicated when multiple people are named on an account, but there is no valid survivorship agreement.
The surviving account holder should not assume that every dollar remaining in the account automatically belongs to them. Instead, the family or estate may need to determine the deceased person’s interest in the account and what should happen to that interest.
For example, a parent may add an adult child to help pay bills or manage finances.
- How the account was originally established
- Whether a survivorship agreement was signed
- Who contributed money to the account
- Whether the account arrangement changed over time
- Why another person was added to the account
- What the deceased owner’s estate planning documents provide
These questions are especially important when another person was added to an account for convenience. A parent, for example, may add an adult child so the child can help pay bills or manage finances. The parent may not have intended for that child to receive the entire balance after death.
Families should therefore review the purpose of the arrangement and the account documents rather than assume that access equals inheritance.
Access to the Account Is Not the Same as Inheritance
Someone may have written checks, made withdrawals, paid bills, or helped manage an account for years. After the original owner dies, that history of access can easily be mistaken for a right to inherit the remaining money.
Those are separate issues.
Someone’s authority during the account owner’s lifetime does not necessarily determine who owns the funds after death. This matters especially when an aging parent adds a child to an account for practical reasons.
What began as a convenient way to manage expenses may later create disagreement among siblings about whether the child was supposed to inherit the money or simply help manage it.
Before anyone withdraws or distributes substantial funds, the family should determine the type of account and review the rights created by its governing documents.
The Will and the Bank Account May Point in Different Directions
A joint account can create an unexpected result when its terms do not match what family members see in the will.
Suppose a parent’s will divides the estate equally among three children, but a substantial bank account also lists one child. If that account has a valid right of survivorship, the funds may pass directly to that child rather than being divided three ways under the will.
Other arrangements can also affect how property transfers after death, including:
- Beneficiary designations
- Trust ownership
- Payable-on-death accounts
- Retirement account beneficiaries
- Life insurance beneficiaries
- Survivorship provisions involving other assets
This is one reason families should not review a will in isolation. The ownership and beneficiary structure of individual assets can be just as important as the instructions contained in the will itself.
A coordinated estate plan considers how these different pieces work together.
Payable-on-Death Accounts Work Differently
Not every bank account that transfers outside probate is a joint account.
A payable-on-death account, often called a POD account, allows an account owner to designate someone to receive the funds after the owner dies. The beneficiary does not need to be a joint owner during the account owner’s lifetime. Texas law recognizes POD accounts as one of several multiple-party account arrangements that can affect how funds transfer after death.
For families reviewing an estate, determining whether someone is a joint owner, survivorship owner, or POD beneficiary can help clarify whether the funds transfer directly or need to be addressed through probate.
Joint Accounts Can Create Unexpected Family Disputes
Disagreements often begin when the legal structure of an account does not match what different family members believe the deceased person intended.
The sibling who appears on the account may believe the parent intended them to receive the remaining balance. Other beneficiaries may expect the will to divide the money among them.
When questions arise, relevant information may include:
- Account agreements and signature cards
- Survivorship or beneficiary designations
- Records showing who contributed the funds
- Changes made to the account over time
- The deceased person’s will or trust
- Communications concerning why the account was created or changed
These disagreements can extend beyond ordinary estate administration when beneficiaries, heirs, executors, or account holders have competing claims to the funds.
Depending on the circumstances, questions about an account may become part of broader estate and inheritance disputes.
Review the Account Agreement, Not Just the Bank Statement
A bank statement can show whose names appear on an account, but it may not reveal all of the terms governing what happens after death.
The underlying account records can provide a clearer picture. Depending on the circumstances, useful documents may include:
- The original account agreement
- Signature cards
- Right of survivorship designations
- Payable-on-death designations
- Documents showing later changes to the account
- Records showing how the account was funded
The financial institution may also have records showing how the account holders set it up and whether they selected a survivorship or beneficiary arrangement.
These documents can become important during the probate process in Texas. They can help the executor or administrator determine which property belongs to the probate estate and which assets may transfer separately.
Coordinating Joint Accounts With Your Estate Plan
Joint accounts are not inherently a problem. They can make everyday financial management easier for married couples and allow a trusted family member to help someone who needs assistance managing expenses.
Problems are more likely when the account terms conflict with the rest of the estate plan.
Families should review joint accounts along with the rest of the estate plan, particularly after:
- Marriage or divorce
- The death of a spouse or another joint owner
- Adding an adult child to help manage finances
- A significant change in assets
- Changes in family relationships
- Creating or updating a will or trust
If you want the surviving account holder to receive the money, the account documents should reflect that intention. If you add someone only to help manage finances, you should also understand what rights the arrangement may create.
The goal is not simply to have a will. It is to make sure the different parts of the estate plan work together.
Understanding Who Is Entitled to the Account
The names on a joint bank account do not always reveal who will inherit the money in Texas.
A valid right of survivorship can allow funds to pass directly to a surviving account holder. A joint account without survivorship rights can produce a different result, while a POD designation creates another type of transfer altogether.
The account documents, ownership arrangement, and circumstances surrounding the account all matter.
At Henington Lewis Law Firm PLLC, we help individuals and families in Austin and Central Texas understand how bank accounts and other assets fit into their estate plans and how to address ownership after someone dies.
If you are planning your estate or have questions about a joint account after a death, contact our firm to discuss the next steps.
Frequently Asked Questions
Does a joint bank account automatically go to the surviving person in Texas?
No. Having two names on an account does not automatically mean the surviving account holder inherits all of the money. Whether the funds pass to the survivor can depend on the type of account and whether a valid right of survivorship was established.
What happens to a joint bank account when one owner dies in Texas?
It depends on how the account holders set it up. If the account includes a valid right of survivorship, the funds may pass directly to the surviving owner. Without survivorship rights, the deceased owner’s interest may need to be addressed through the estate.
Does a will override a joint bank account in Texas?
Not necessarily. If a joint account has a valid right of survivorship, the funds may transfer outside probate and may not be controlled by the terms of the deceased person’s will. This is why bank account designations should be coordinated with the overall estate plan.
What is the difference between a joint account and a payable-on-death account?
A joint account may give multiple owners rights to the account while they are alive. With a payable-on-death (POD) account, the designated beneficiary generally receives the funds after the account owner dies but does not have the same ownership rights during the owner’s lifetime.
Can a joint bank account become part of probate in Texas?
Yes, depending on how the account was structured. If the deceased owner’s interest does not pass through a valid survivorship or other non-probate arrangement, that interest may become part of the probate estate.
What documents should I check after a joint account owner dies?
Start with the account agreement and any documents showing how the account holders originally structured or later changed it. Signature cards, survivorship provisions, POD designations, and related bank records may help determine what happens to the funds after death.
Our Austin, TX Office Location
Related Posts
Planning for Couples With Unequal Assets or Incomes
If one spouse stopped earning tomorrow, would the other person's accounts, property, and estate planning documents provide the financial protection they assume is already there?For couples with significantly different incomes or assets, that question can reveal gaps that are easy to overlook while both spouses…
What Happens If Your Executor Dies Before You?
Naming an executor is an important part of creating a will, but that choice may have been made years or even decades before the executor is ever needed. If the person you selected dies before you, your will does not automatically become invalid.What happens next…
Second Marriages: Protecting Your Spouse and Your Family
A second marriage can bring together two financial lives that were built long before the relationship began. Each spouse may enter the marriage with a home, retirement savings, investments, business interests, or property intended for children from a previous relationship.That can make estate planning more…
Your 40s Are a Critical Time to Review Your Will and Trust
By your 40s, your financial and family life may look very different from when you first created an estate plan. A will or trust prepared years ago may still reflect an earlier stage of your life, even as your family, property, savings, and responsibilities have…
Joint Bank Accounts: Who Actually Inherits the Money?
Married couples and families often use joint bank accounts to share financial responsibilities. However, having two names on an account does not always mean the surviving account holder will automatically inherit the money when the other person dies.In Texas, the outcome can depend on how…
Lost or Missing Wills in Texas: What Families Need to Know
The family knows a will exists. Maybe someone remembers signing as a witness, the executor has an old copy, or an attorney prepared the document years ago. But when it is time to settle the estate, the original will is nowhere to be found.That missing…
Whether you need a personalized estate plan or help handling a civil dispute, we're here to help
Take the first step toward protecting your legacy and giving your family lasting peace of mind. Whether you need a personalized estate plan or help handling a civil dispute, we're here to help.


Quick Links
Disclaimer: This website is for informational purposes only and constitutes an attorney advertisement. The content on this site is not intended to provide legal advice or create an attorney-client relationship. Viewing or interacting with this website does not establish such a relationship between you and our firm. Do not send confidential or sensitive information through this website or its contact forms. Communications through the website are not secure and may not be protected under attorney-client privilege. If you require legal advice or representation, please contact our office directly to arrange a consultation. The information provided on this site is general in nature and may not apply to your specific situation. You should consult an attorney for advice tailored to your circumstances. Past outcomes or case results referenced on this site do not guarantee future results. Every legal matter is unique, and results depend on the specific facts and applicable law. Jurisdictional Limitation: Our firm is licensed to practice law in Texas. This website is not intended to solicit clients outside of this jurisdictions. Copyright Notice: All content on this site is copyrighted and may not be reproduced without permission.
© 2026 Henington Lewis Law Firm PLLC. All Rights Reserved.