Planning for Couples With Unequal Assets or Incomes
If one spouse stopped earning tomorrow, would the other person’s accounts, property, and estate planning documents provide the financial protection they assume is already there?
For couples with significantly different incomes or assets, that question can reveal gaps that are easy to overlook while both spouses are alive and managing the household together. Retirement savings may be concentrated in one name, a home or business may belong primarily to one spouse, and inherited property may have its own considerations. Estate planning provides a way to look at those differences together and determine what would actually happen if either spouse could no longer manage the financial role they have today.
Understanding Financial Imbalances in an Estate Plan
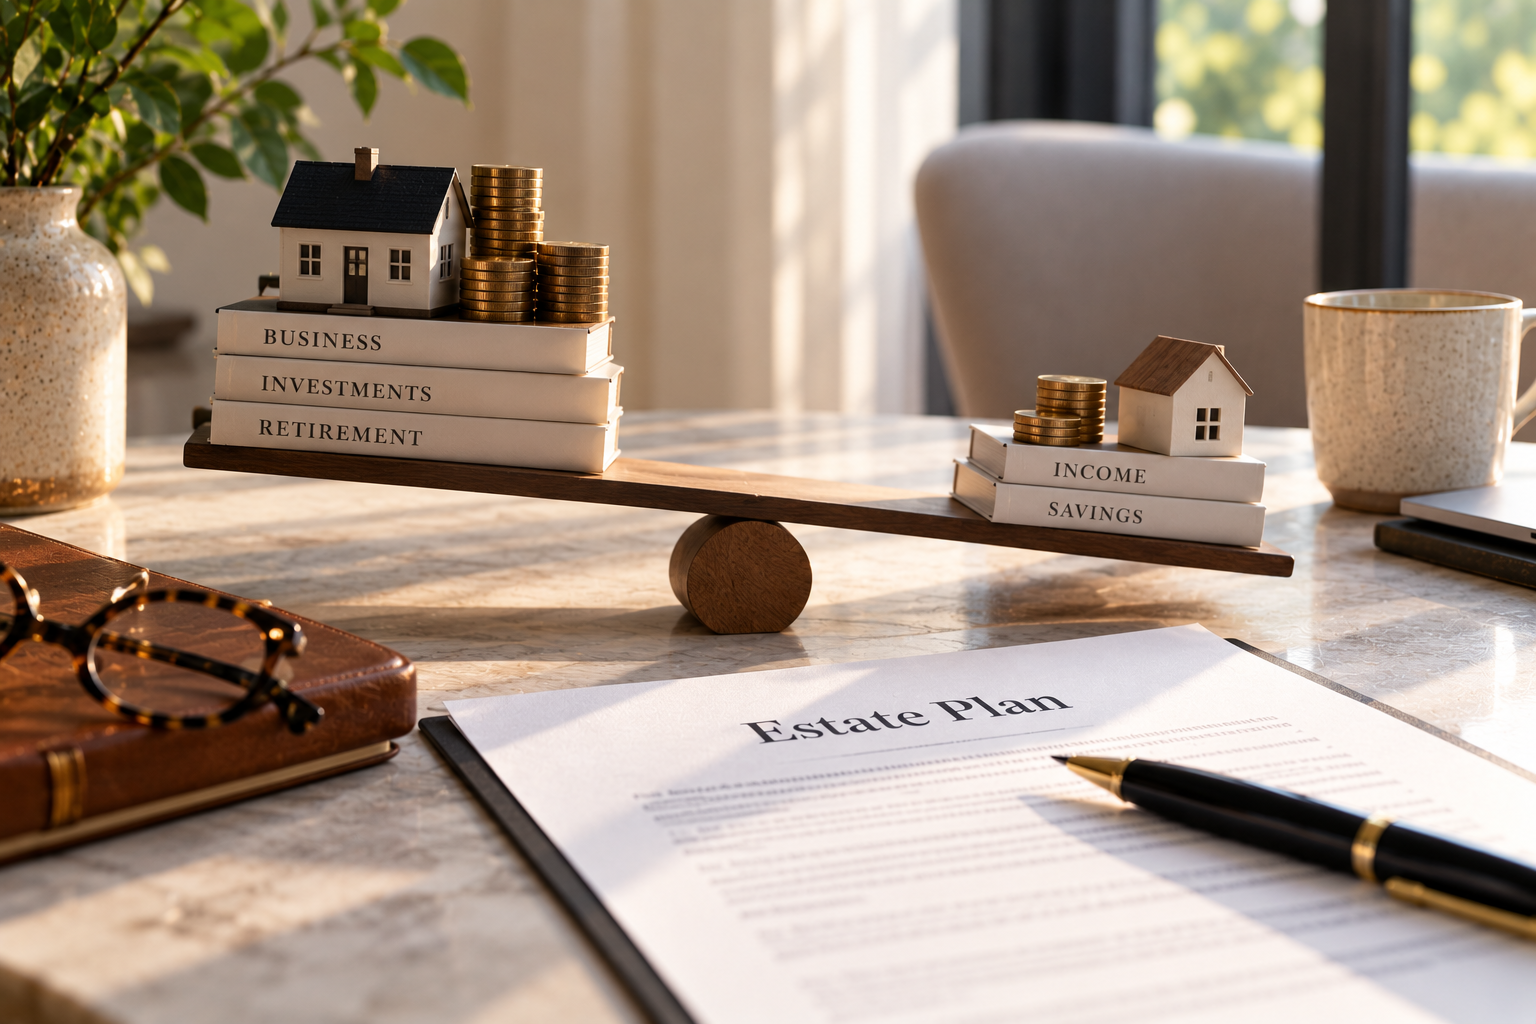
Unequal finances are not limited to differences in salary. They can develop gradually through career decisions, property ownership, inheritances, business interests, investment growth, or time spent outside the workforce.
For estate planning purposes, what matters is not simply which spouse has the higher net worth. It is understanding where the household’s financial security actually sits and what would happen to those resources after death or incapacity.
A couple’s financial picture may include:
- Retirement savings concentrated in one spouse’s name
- Real estate owned individually or together
- Business interests
- Investment and brokerage accounts
- Inherited assets
- Life insurance
- Joint and individual financial accounts
- Property acquired before the marriage
Some of those assets may pass through a will or trust, while others may transfer through beneficiary designations, ownership arrangements, or other mechanisms. Understanding the difference between probate and non-probate assets provides a clearer starting point for evaluating how the overall plan would work.
Unequal Income Can Create Different Financial Needs
Income differences can affect more than how much each spouse saves.
A higher-earning spouse may fund a larger portion of the mortgage, household expenses, retirement savings, insurance, or education costs. If that income disappears, the surviving spouse may need to continue many of those same financial responsibilities with very different resources.
That can make it useful to consider expenses such as:
- Mortgage and housing costs
- Health and other insurance
- Everyday household expenses
- Education costs
- Outstanding debts
- Long-term savings needs
- Costs associated with maintaining property
The goal is not necessarily to equalize what each spouse owns. It is to understand whether the surviving spouse would have access to the resources needed to manage the financial life the couple built together.
Property Ownership Can Affect the Plan
When one spouse owns significantly more property, understanding how that property is characterized becomes important.
Texas distinguishes between separate and community property. Property acquired during marriage is generally presumed to be community property, while property owned before marriage or received by gift or inheritance may qualify as separate property.
This distinction can become particularly relevant when one spouse:
- Entered the marriage owning a home or other real estate
- Received a substantial inheritance
- Built a business before the marriage
- Has significant investments accumulated earlier in life
- Owns property separately from the other spouse
Property ownership and marital property rules can affect what each spouse can transfer and what happens when one dies. For that reason, estate planning should begin with a clear understanding of how major assets are owned rather than assuming that marriage alone determines the outcome.
A Will May Control Only Part of the Wealth
A will can provide important instructions, but it does not necessarily control every asset a couple owns.
Retirement accounts, life insurance policies, payable-on-death accounts, and certain other financial assets may transfer according to beneficiary designations or account arrangements.
That distinction becomes especially important when a large portion of the household’s wealth is concentrated in accounts belonging to one spouse.
For example, a couple may have wills that divide property one way while a retirement account names a beneficiary who causes a substantial portion of the wealth to transfer differently. The documents may each be valid while still producing an overall result the couple did not expect.
This is why beneficiary designations should be reviewed alongside wills and trusts. The same consideration applies to 401(k)s and other retirement accounts.
A Trust Can Address More Than Who Inherits
When spouses have significantly different assets, the planning question may not simply be who receives property after death. Couples may also want to decide how assets should be managed and used over time.
Depending on the circumstances, a trust can provide greater control over those decisions.
A trust may be designed to:
- Provide financial support for a surviving spouse
- Establish how certain assets can be used
- Manage property for children or other beneficiaries
- Set instructions for future distributions
- Provide continuity in managing particular assets
- Determine what happens to remaining property later
Not every couple with unequal wealth needs a trust. The value of a trust depends on the assets involved, the beneficiaries, and what the couple wants to accomplish.
For couples considering this approach, understanding what assets should be placed in a trust can help clarify how the trust would fit into the broader plan.
Inherited Wealth May Come With Different Goals
A financial imbalance can also develop suddenly.
One spouse may inherit money, real estate, investments, or an interest in a family business. While that inheritance may become an important part of the couple’s financial life, the spouse who received it may also have specific ideas about where the property should eventually go.
For example, someone may want an inheritance to help support a spouse during their lifetime while ultimately preserving certain assets for children or other relatives.
Those goals should be addressed deliberately rather than assumed.
Inherited property can raise questions about ownership, management, beneficiary choices, and how the inheritance should coordinate with the rest of the estate. Addressing those issues while both spouses can participate in the planning process can make the intended outcome clearer.
Business Ownership Requires a Different Conversation
For some couples, the largest financial imbalance is not sitting in a bank account. It is tied up in a business.
A business can represent a substantial portion of one spouse’s wealth while providing much of the household’s income at the same time. If that spouse dies or becomes incapacitated, the family could face questions involving both ownership and ongoing financial support.
Planning may need to consider:
- Who should receive the ownership interest
- Whether the surviving spouse should be involved in the business
- Who is capable of managing operations
- Whether there are other owners or partners
- How the surviving spouse would receive financial support
- Whether the business should eventually pass to children or other beneficiaries
Simply transferring a business interest does not necessarily replace the income or management role the owner previously provided. The business therefore needs to be considered as part of the household’s broader estate plan.
Incapacity Can Expose Financial Gaps Too
Death is not the only event that can reveal an imbalance between spouses.
In some households, one spouse handles most investments, manages the business, communicates with financial professionals, or oversees major accounts. If that person becomes unable to manage those responsibilities, the other spouse may suddenly need access to financial information and authority they have never previously needed.
Planning for incapacity may involve reviewing:
- Financial powers of attorney
- Medical decision-making documents
- Trust provisions
- Access to important financial information
- Authority to manage property or business interests
- The people chosen to step in when necessary
These arrangements can be particularly important when financial responsibilities are concentrated with one spouse rather than shared equally.
Equal Is Not Always the Same as Fair
A balanced estate plan does not necessarily require every asset to be divided in half.
Different assets may need to accomplish different goals. The surviving spouse may need continued access to the home and enough resources to cover living expenses. A business may need to pass to someone capable of operating it. Other assets may be intended for children or family members.
Looking at each asset separately can make the plan seem uneven even when the overall arrangement reflects what the couple wants.
A more useful approach is to consider how the pieces work together:
- What does the surviving spouse need?
- Which assets can provide income or liquidity?
- Are there assets intended for other beneficiaries?
- Does either spouse want certain property to remain within their family?
- How will beneficiary-designated accounts affect the overall distribution?
- Who should manage assets that cannot simply be divided?
The answers may lead to different distributions for different assets while still creating a coordinated plan.
Both Spouses Should Know How the Plan Works
When one spouse earns substantially more or controls most of the household’s assets, important financial decisions can gradually become concentrated with that person.
Estate planning is an opportunity to make those arrangements visible to both spouses.
Each spouse should understand:
- Which assets are owned individually and jointly
- Where major financial accounts are held
- Who is named as beneficiary
- Which assets would pass through probate
- What the surviving spouse would receive
- How ongoing household expenses could be supported
- Who could manage finances during incapacity
- Whether certain assets are intended for other beneficiaries
A coordinated estate and legacy plan can bring those decisions together rather than relying on assumptions about what will happen.
Plan for the Financial Life You Actually Have
Unequal assets or incomes do not necessarily require a more complicated estate plan. They do require a clear understanding of where the household’s wealth is held, how it would transfer, and what each spouse would need if the other were no longer able to contribute financially.
Reviewing wills, trusts, beneficiary designations, property ownership, business interests, and incapacity documents together can reveal gaps that may not be obvious when each piece is considered separately.
Henington Lewis Law Firm PLLC helps couples in Austin and Central Texas create estate plans that reflect their property, financial responsibilities, and long-term goals. If you and your spouse have significantly different assets or incomes, contact our firm to discuss how your estate plan can address those differences.
Frequently Asked Questions
How should couples with different incomes approach estate planning?
Couples should look beyond how much each person earns and consider where their assets are held, how property is owned, which accounts have beneficiary designations, and what each spouse would need if the other died or became incapacitated. The goal is to coordinate those pieces within the overall estate plan.
Does the higher-earning spouse need a different estate plan?
Not necessarily a separate plan, but differences in income and asset ownership may require additional consideration. If most retirement savings, business interests, or other significant assets are concentrated with one spouse, the couple should consider how the other spouse would be financially protected.
Does my spouse automatically have access to assets in my name if I die?
Not always. What happens to an asset can depend on the type of property, how it is owned, whether there is a beneficiary designation, and the estate planning documents in place. Marriage alone does not mean every individually held asset will transfer in the same way.
Should both spouses be beneficiaries of each other’s retirement accounts?
The appropriate beneficiary designation depends on the type of retirement plan, applicable rules, and the couple’s goals. Retirement accounts should be reviewed as part of the broader estate plan rather than assuming the will determines who receives them.
Can a trust protect a lower-earning spouse?
Depending on how it is structured, a trust can provide financial support for a surviving spouse while establishing instructions for how assets are managed and eventually distributed. Whether a trust is appropriate depends on the couple’s assets, beneficiaries, and long-term goals.
How should inherited property be handled when one spouse has significantly more assets?
Inherited property may require separate consideration because the spouse who received it may have specific goals for its use and eventual distribution. The estate plan can address how that property should benefit a surviving spouse while also considering children or other intended beneficiaries.
Our Austin, TX Office Location
Related Posts
Planning for Couples With Unequal Assets or Incomes
If one spouse stopped earning tomorrow, would the other person's accounts, property, and estate planning documents provide the financial protection they assume is already there?For couples with significantly different incomes or assets, that question can reveal gaps that are easy to overlook while both spouses…
What Happens If Your Executor Dies Before You?
Naming an executor is an important part of creating a will, but that choice may have been made years or even decades before the executor is ever needed. If the person you selected dies before you, your will does not automatically become invalid.What happens next…
Second Marriages: Protecting Your Spouse and Your Family
A second marriage can bring together two financial lives that were built long before the relationship began. Each spouse may enter the marriage with a home, retirement savings, investments, business interests, or property intended for children from a previous relationship.That can make estate planning more…
Your 40s Are a Critical Time to Review Your Will and Trust
By your 40s, your financial and family life may look very different from when you first created an estate plan. A will or trust prepared years ago may still reflect an earlier stage of your life, even as your family, property, savings, and responsibilities have…
Joint Bank Accounts: Who Actually Inherits the Money?
Married couples and families often use joint bank accounts to share financial responsibilities. However, having two names on an account does not always mean the surviving account holder will automatically inherit the money when the other person dies.In Texas, the outcome can depend on how…
Lost or Missing Wills in Texas: What Families Need to Know
The family knows a will exists. Maybe someone remembers signing as a witness, the executor has an old copy, or an attorney prepared the document years ago. But when it is time to settle the estate, the original will is nowhere to be found.That missing…
Whether you need a personalized estate plan or help handling a civil dispute, we're here to help
Take the first step toward protecting your legacy and giving your family lasting peace of mind. Whether you need a personalized estate plan or help handling a civil dispute, we're here to help.


Quick Links
Disclaimer: This website is for informational purposes only and constitutes an attorney advertisement. The content on this site is not intended to provide legal advice or create an attorney-client relationship. Viewing or interacting with this website does not establish such a relationship between you and our firm. Do not send confidential or sensitive information through this website or its contact forms. Communications through the website are not secure and may not be protected under attorney-client privilege. If you require legal advice or representation, please contact our office directly to arrange a consultation. The information provided on this site is general in nature and may not apply to your specific situation. You should consult an attorney for advice tailored to your circumstances. Past outcomes or case results referenced on this site do not guarantee future results. Every legal matter is unique, and results depend on the specific facts and applicable law. Jurisdictional Limitation: Our firm is licensed to practice law in Texas. This website is not intended to solicit clients outside of this jurisdictions. Copyright Notice: All content on this site is copyrighted and may not be reproduced without permission.
© 2026 Henington Lewis Law Firm PLLC. All Rights Reserved.